Could the right car loan be less about finding the lowest advertised rate and more about finding an option that fits your circumstances? A car finance broker Australia buyers work with can compare options from a panel of lenders and help organise an application. The lender provides the funds and decides whether to approve the loan, so approval is never guaranteed.
It’s understandable to feel unsure when loan terms, fees and eligibility rules differ between lenders. You may also want to know what happens to your credit file when you apply, and whether speaking with a broker commits you to borrowing. These are practical questions to raise before you decide whether to proceed.
This guide explains what a car finance broker does at each stage, from discussing your needs and comparing options to supporting an application. You’ll learn what to compare, including the interest rate, comparison rate, fees and key loan terms, and what to ask about credit checks and remuneration. The aim is to help you make a considered decision based on the terms, not just a headline rate or an approval estimate.
Key Takeaways
- A car finance broker Australia buyers work with can arrange finance through multiple lenders, while the lender provides the funds.
- Compare the comparison rate, fees, repayment structure, loan term and total amount repayable, not just the advertised rate.
- Ask how the broker is paid and how remuneration relates to the finance options presented.
- Accurate income, expense, vehicle and finance details can help support the application process.
- Speaking Finance arranges car finance through a panel of more than 70 lenders, but loan approval isn’t guaranteed.
What does a car finance broker in Australia do?
A car finance broker helps arrange finance by acting as an intermediary between you and potential lenders. They can discuss what you need, explore options from their lender panel, explain key differences and help prepare an application. The lender, not the broker, provides the funds and decides whether to approve the loan.
That distinction matters. A broker can help you understand the process and coordinate communication, but can’t promise approval, a particular interest rate or a specific loan outcome. The options available depend on your circumstances, the vehicle and each lender’s criteria. For a general overview of how vehicle loans work, see Car finance explained.
How is a broker different from going directly to a lender?
A direct application lets you consider that lender’s own products and criteria. A broker may be able to explore options across a lender panel, giving you more to compare without approaching each lender separately. A larger panel doesn’t mean every lender will be relevant or that approval is assured, so focus on the terms that suit your situation.
A broker can also help put the differences into plain language. For example, compare the interest rate, fees, repayment frequency and loan term, rather than assuming the option with the lowest headline rate will cost less overall. The aim is to understand the terms before deciding whether to apply.
Who might find a car finance broker useful?
A broker may be useful if you’re still choosing a vehicle and want to understand finance options before settling on a budget. They can also help employed buyers organise an application, or help self-employed and business buyers discuss how their income or vehicle use may shape the information lenders need. The lender’s criteria determine which options may be available.
If you prefer one point of contact, a broker can help coordinate questions, documents and lender communication through the process. A car finance broker Australia buyers choose should clarify the steps and options, while leaving the decision to proceed in your hands.
Before you apply, be ready to talk through your needs and finances openly. Clear, accurate information helps a broker understand your situation and discuss relevant options. Take time to compare what’s presented, ask about anything that’s unclear and decide whether to move forward.
How can a car finance broker compare options for your needs?
A useful comparison starts with your situation, not a headline rate. The vehicle you’re considering, your deposit, the repayments your budget can manage and how you’ll use the car can all shape which options are worth examining. A car finance broker Australia buyers work with can organise options around those details and help you understand the differences.
Which car loan details deserve a closer look?
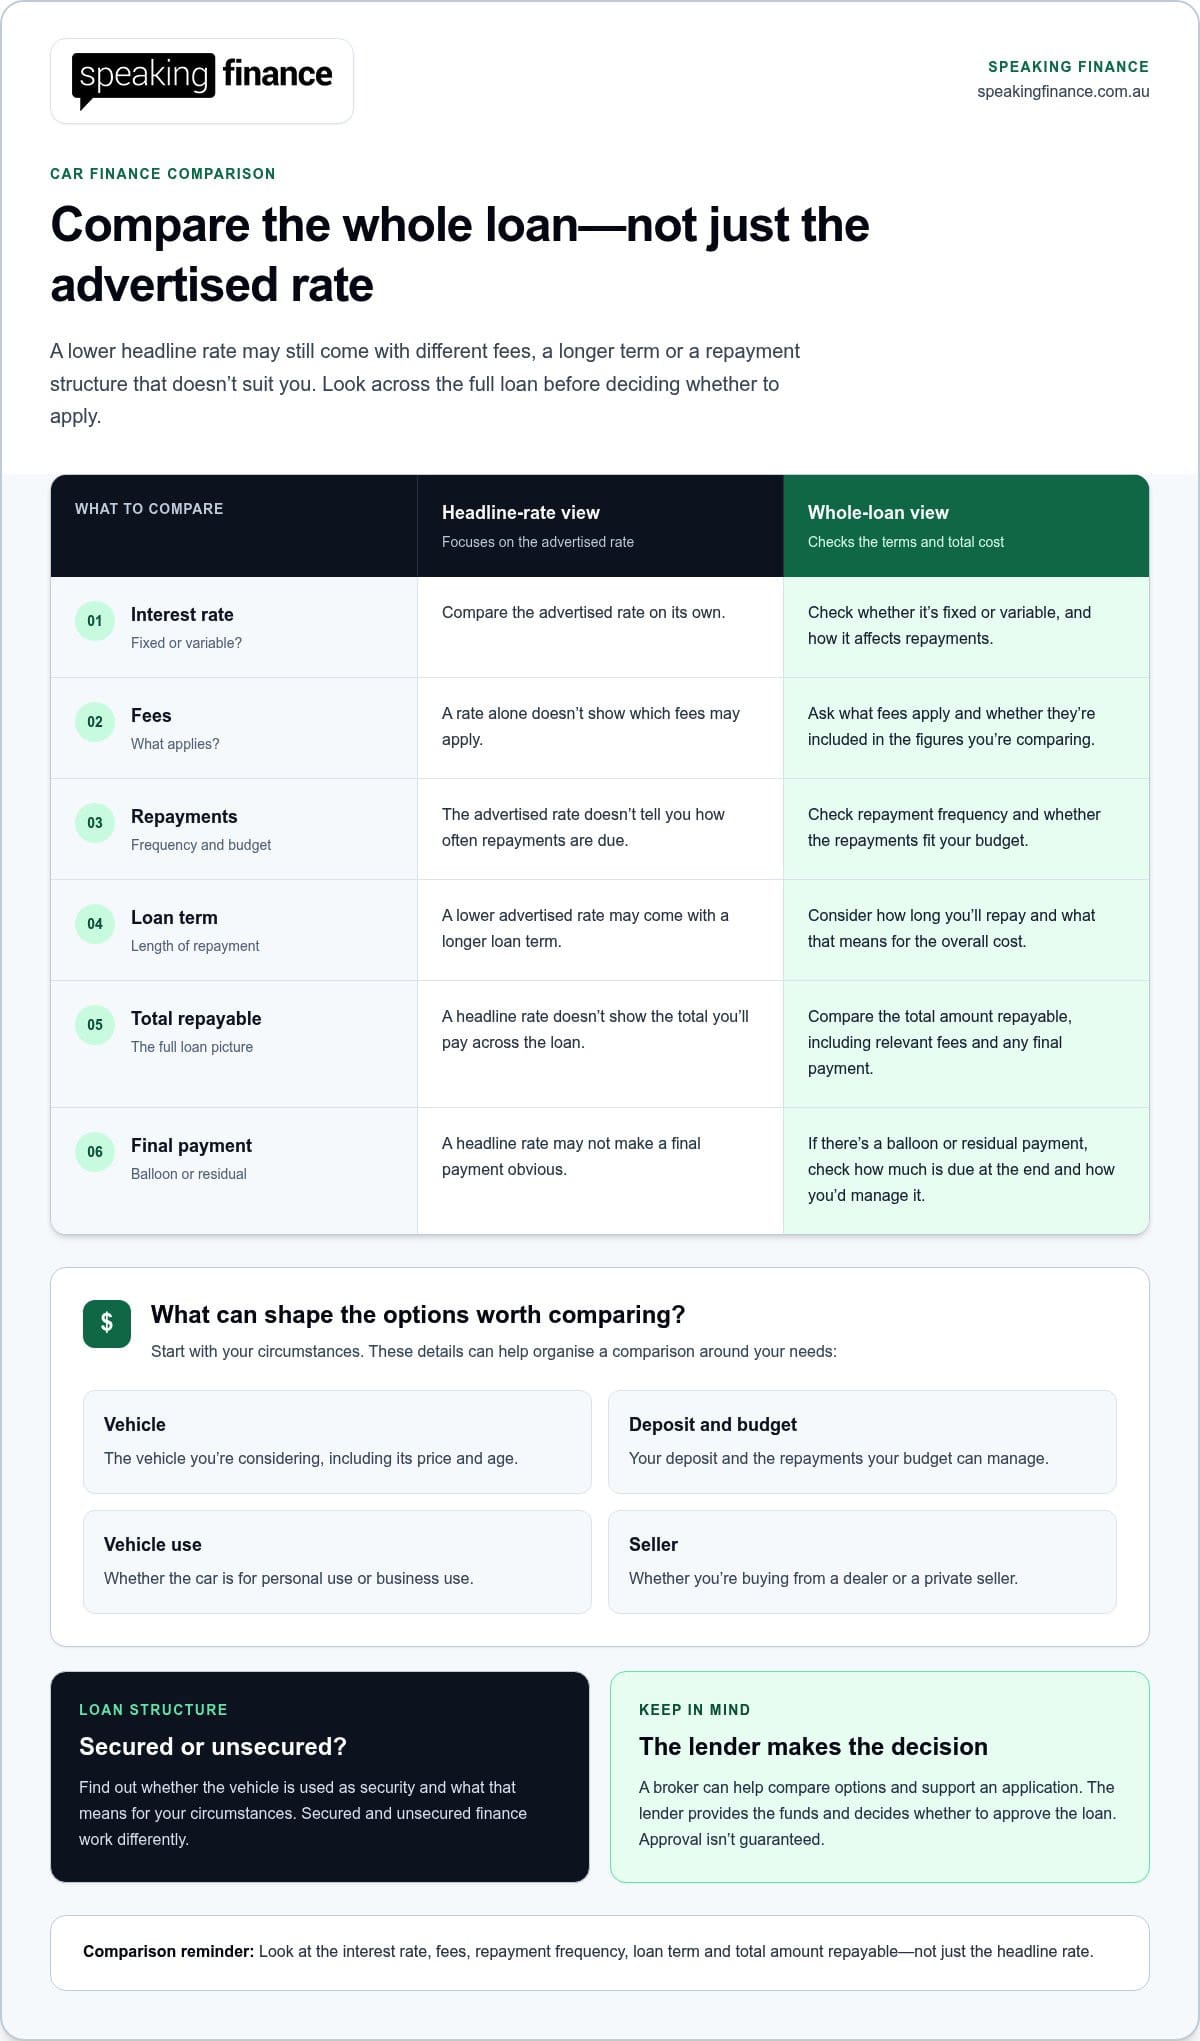
Look beyond the advertised interest rate. Compare the full cost and repayment setup, and check whether a feature changes what you’ll owe during or at the end of the loan.
- Interest rate: Is it fixed or variable, and how does it affect repayments?
- Fees: What fees apply, and are they included in the figures you’re comparing?
- Repayments: How often are they due, and do they fit your budget?
- Loan term: How long will you be repaying, and what does that mean for the overall cost?
- Total amount repayable: What will you pay across the loan, including relevant fees and any final payment?
A lower advertised rate may still come with a longer term, different fees or a repayment structure that doesn’t suit you. If a loan includes a balloon or residual payment, check how much is due at the end and consider how you would manage it. Secured and unsecured finance also work differently, so find out whether the vehicle is used as security and what that means for your circumstances. Australian government guidance on car loans offers further information about loan features and comparison.
How does the vehicle and its use affect finance options?
A car for personal use may be assessed differently from a vehicle sought for business use. Be ready to explain the intended use, the vehicle’s price and age, and whether you’re buying from a dealer or private seller. Lender criteria vary, and not every lender will consider every vehicle or borrower profile.
For a broader introduction, read Car finance options: A clear guide for buyers, then use How to compare car finance options as a checklist when weighing up the details. If you’d like support organising a comparison around your needs, explore car finance support with Speaking Finance.
What should you understand about broker fees, commissions and suitability?
Before moving ahead, get a clear picture of how the broker is paid, who the lender is and what the proposed loan will require from you. Remuneration arrangements can differ. A broker may receive commission from a lender, and a client fee may also apply. Ask for the details, including whether you will pay a fee and how the remuneration relates to the options being discussed.
Commission alone doesn’t tell you whether a loan is suitable or mean that your rate will automatically change. Focus on the full picture: the broker’s role, the lender providing the funds, any fees that apply to you and the loan terms. A car finance broker Australia borrowers work with should be able to explain these points in plain English, without promising approval or a particular rate.
How can a borrower ask about broker remuneration?
Ask directly: “How are you paid, and will I pay a fee?” Then check when any fee may apply, how it will be explained and where relevant costs appear in the loan information. Make sure you understand the remuneration arrangement before deciding to proceed. If the answer is unclear, ask for a simpler explanation or a written breakdown so you can consider it alongside the loan terms.
These are reasonable questions, not awkward ones. Clear information helps you understand the relationship between the broker and lender, and what the arrangement means for your decision. It doesn’t, on its own, tell you whether the loan is right for your circumstances.
What does a suitable loan decision involve?
Approval likelihood isn’t the same as suitability. A loan might be available but still have repayments, a term or features that don’t work for your budget or intended vehicle use. Consider whether you can manage the repayments alongside your other commitments, and whether the loan structure fits how long you expect to keep the car.
Before committing, review the proposed terms at your own pace. Ask what each fee covers, how repayments are set, and whether any final balloon or residual payment applies. If loan language is unfamiliar, use Car finance terms explained in plain English as a prompt for what to clarify. Compare the information in front of you, ask for plain-English answers and proceed only when you understand what you’re agreeing to.
What happens when you apply for car finance through a broker?
Applying through a broker is a guided process, but you stay in control of whether to proceed. The broker helps organise your information and communicate with lenders. Each lender assesses the application and makes its own decision. Here’s how the steps may look:
- 1. Discuss your plans. Talk through the vehicle you’re considering, how you’ll use it, your budget and the type of finance you’re looking for. You can raise questions before deciding whether to apply.
- 2. Share relevant details and documents. The broker may ask about your identity, income, employment, living costs and existing financial commitments. Vehicle details and your deposit plans may also be relevant.
- 3. Review possible options. With your information, the broker can help organise options from lenders on their panel and explain what differs between them. An option to consider isn’t a promise of approval.
- 4. Decide whether to apply. If you choose to proceed, the application is sent to the lender. Check that the details are accurate and that you understand the terms before moving forward.
- 5. Respond to lender requests. The lender may ask for more information or documents. Your broker can help pass on requests and explain the next steps, while the lender remains responsible for its assessment and decision.
What information may help start the conversation?
Prepare what you can, but you don’t need to know every answer before an initial discussion. Depending on your circumstances and the vehicle, useful details may include:
- Proof of identity and information about your income and employment
- Your regular living costs and existing financial commitments
- The vehicle’s details, price and seller information, if you’ve chosen one
- Your deposit plans and the amount of finance you’re considering
Be accurate and let the broker know if something has changed or you’re unsure. You can also ask how documents will be handled and what information is needed at each stage. For practical preparation tips, see Common car finance application mistakes.
What happens after the lender receives an application?
The lender reviews the information against its own criteria and determines whether to approve the application, decline it or offer finance with conditions. The broker can help explain requests and communicate next steps, but can’t control the lender’s decision. Approval, any conditions and settlement timing depend on the lender and the details of the application. Ask what credit checks may take place and when, rather than assuming the process will have a particular effect on your credit file.
If you’re ready to talk through your circumstances and the application steps, talk through your car finance plans with Speaking Finance. Speaking Finance arranges car finance through lenders; it isn’t the lender providing the funds.
How can Speaking Finance help with car finance in Australia?
Looking for a car finance broker Australia-wide? Speaking Finance arranges car finance through a panel of more than 70 lenders, helping customers discuss their needs, understand options and work through application steps. Speaking Finance is a broker, not a direct lender: the lender provides the funds and makes its own decision about an application.
The value is having support to bring the moving parts together. Your budget, the vehicle you’re considering and how you intend to use it can all inform the finance discussion. A broker can help organise relevant options and explain what to consider, while keeping the decision to apply in your hands. The lender determines approval and loan terms, so no particular outcome can be promised.
What support can a Speaking Finance broker provide?
Speaking Finance can guide you through finance discussions, help you make sense of options and support you as an application progresses. If you’re weighing up a car for personal use against a vehicle for business, explain the intended use and your priorities. That context can help shape a useful conversation about the options available through the lender panel.
Speaking Finance also offers a car-buying service. It’s a separate support option for buyers who would like help with the vehicle search as well as a discussion about finance. You can consider either service in light of what you need.
What is a sensible next step for a car buyer?
You don’t need to have every detail settled before starting a conversation. A few notes can help make it more focused:
- Your budget and the repayments you’re comfortable discussing
- Vehicle details, if you’ve already chosen a car
- How you plan to use the vehicle
- Questions about loan features, fees, repayments and broker remuneration
As you review any options, take time to understand the proposed loan terms and how the broker is paid, including whether any client fee applies. Ask for plain-English explanations if something isn’t clear. You can then decide whether an option suits your circumstances and whether you want to proceed with an application.
If you’d like to talk through your plans without committing to a loan, speak with Speaking Finance about your car finance options. A conversation can help you clarify what you’re looking for and understand the next steps, without a promise of approval or a particular rate.
Take your next car finance step with confidence
A car finance broker Australia buyers work with can help organise options across lenders, guide an application and explain terms worth comparing. The best choice isn’t simply the lowest advertised rate or the option most likely to be approved. Consider repayments, fees and loan features alongside your budget and how you’ll use the vehicle.
Speaking Finance arranges car finance through a panel of more than 70 lenders. It doesn’t lend directly or guarantee approval. It operates through 4 You Finance Pty Ltd, an Australian Credit Licence holder (licence number 533666). Support is available through finance discussions and applications, with a car-buying service as a separate option.
Before deciding, make sure you understand the proposed loan terms and how the broker is remunerated. You can start by discussing your plans and questions, without committing to a loan. Talk through your car finance plans with Speaking Finance and take the next step with a clearer understanding of your options.
Frequently Asked Questions
What does a car finance broker do in Australia?
A car finance broker helps arrange finance by discussing your needs, comparing options from lenders and supporting you through an application. The lender provides the funds and decides whether to approve the loan. A car finance broker Australia-wide, such as Speaking Finance, can arrange options through a panel of more than 70 lenders, but available choices depend on your circumstances, vehicle and lender criteria.
Is it better to use a car finance broker or go directly to a bank?
It depends on how you want to compare finance. A direct application lets you consider one bank’s products, while a broker may explore options from multiple lenders and help explain differences in rates, fees and loan features. Neither approach guarantees approval or a suitable loan. Compare the full terms, including repayments and the total amount repayable, and choose the process that helps you make a considered decision.
How does a car finance broker get paid?
Broker remuneration arrangements can differ. A broker may receive commission from a lender when finance is completed, and a fee paid by the customer may also apply. Ask how the broker is paid, whether any client fee applies and when it would be payable. Have the arrangement explained clearly before deciding to proceed, and consider it alongside the lender, loan terms and options being presented.
Can a car finance broker guarantee loan approval?
No. A broker can help organise an application and discuss options, but cannot guarantee that a lender will approve it. The lender assesses your application against its own criteria and makes the decision, including any conditions. Be cautious of promises of guaranteed approval or a particular rate. Before applying, make sure the proposed repayments and loan features make sense for your budget, even if approval appears possible.
Does applying through a car finance broker affect my credit score?
It can depend on what checks take place and when an application is submitted. Before proceeding, ask whether an initial discussion or assessment involves a credit check, who will conduct it and whether your consent is needed. Also clarify when your details may be sent to a lender. Don’t assume that speaking with a broker and submitting a formal application have the same effect on your credit file.
What information do I need to give a car finance broker?
You may be asked for identity details, information about your income and employment, regular living costs and existing financial commitments. If you’ve chosen a vehicle, its details, price and seller information may also help, along with your deposit plans. The information needed can vary with your circumstances and the lender’s requirements. Provide accurate details, and ask how documents will be handled if you’re unsure.
Can a car finance broker help with a car bought for business use?
A broker can discuss finance options for a vehicle intended for business use. Explain how the car will be used, who will own or use it, your budget and the vehicle details, as these may affect which lender options are relevant. Lenders set their own criteria, so eligibility and available terms vary. A broker can help organise the discussion and application, but the lender makes the final decision.