Could the car loan that looks easiest to arrange be the wrong fit for your budget? If you’re considering a car finance broker in Australia, it helps to know what a broker does, what to compare and what to have ready before you start an application.
A broker isn’t a lender. They can help you compare options from lenders on their panel, explain how loan terms differ and guide you through the application process. The lender assesses your application and decides whether to approve it, so a broker can’t promise approval.
It’s reasonable to have questions about fees, commissions and the overall cost of a loan. This guide explains what to expect, from the first conversation to applying, and how personal car finance differs from business vehicle finance. You’ll also find practical points to check before deciding whether broker support makes sense for you.
Key Takeaways
- A car finance broker Australia-wide can help you explore options from different lenders, but the lender decides whether to approve an application.
- Compare the interest rate, fees, repayment frequency, loan term and total amount repayable, rather than judging a loan by one figure.
- Ask how the broker is paid and whether you’ll pay any separate fees before proceeding.
- Set a realistic budget and have your vehicle details, income, expenses and existing commitments ready for the conversation.
What does a car finance broker in Australia do?
A car finance broker helps you explore and arrange finance through lenders. A car finance broker in Australia can explain options from lenders on their panel, while the lender assesses your application and decides whether to approve it.
The broker’s role is to understand what you want to finance and discuss options that may suit your circumstances. The types of vehicle finance available can vary, as outlined in this Vehicle finance overview. A broker can guide you through the process, but can’t promise approval, a particular rate or savings.
How is a broker different from a lender?
A lender provides the finance and makes its own decision on your application. A broker doesn’t lend you the money. Instead, they help you explore options from lenders they work with and understand how those options differ. Lenders can have different products, criteria and documentation requirements, so an option available through one lender may not be available through another or suit your circumstances.
When might a car buyer consider using a broker?
Broker support may be useful if you want help comparing finance options before committing to a car, or guidance with the application process. It isn’t essential for every buyer. Some prefer to approach a lender directly, while others value having options explained in one conversation.
Be clear about how you intend to use the vehicle:
- Personal car finance: for a vehicle you’re buying for personal use.
- Business vehicle finance: for a vehicle intended for business use, such as a work ute.
The finance structure and relevant considerations can differ depending on the vehicle’s use. Explain its purpose at the start of the conversation so the options discussed reflect your situation.
How does a car finance broker compare loan options?
A car finance broker in Australia can help you compare options across the lenders on their panel. A useful comparison goes beyond the advertised rate: your budget, deposit, vehicle and how you’ll use it all help shape which options are worth considering. Lender products, criteria and documentation requirements also differ.
Which car loan details are worth comparing?
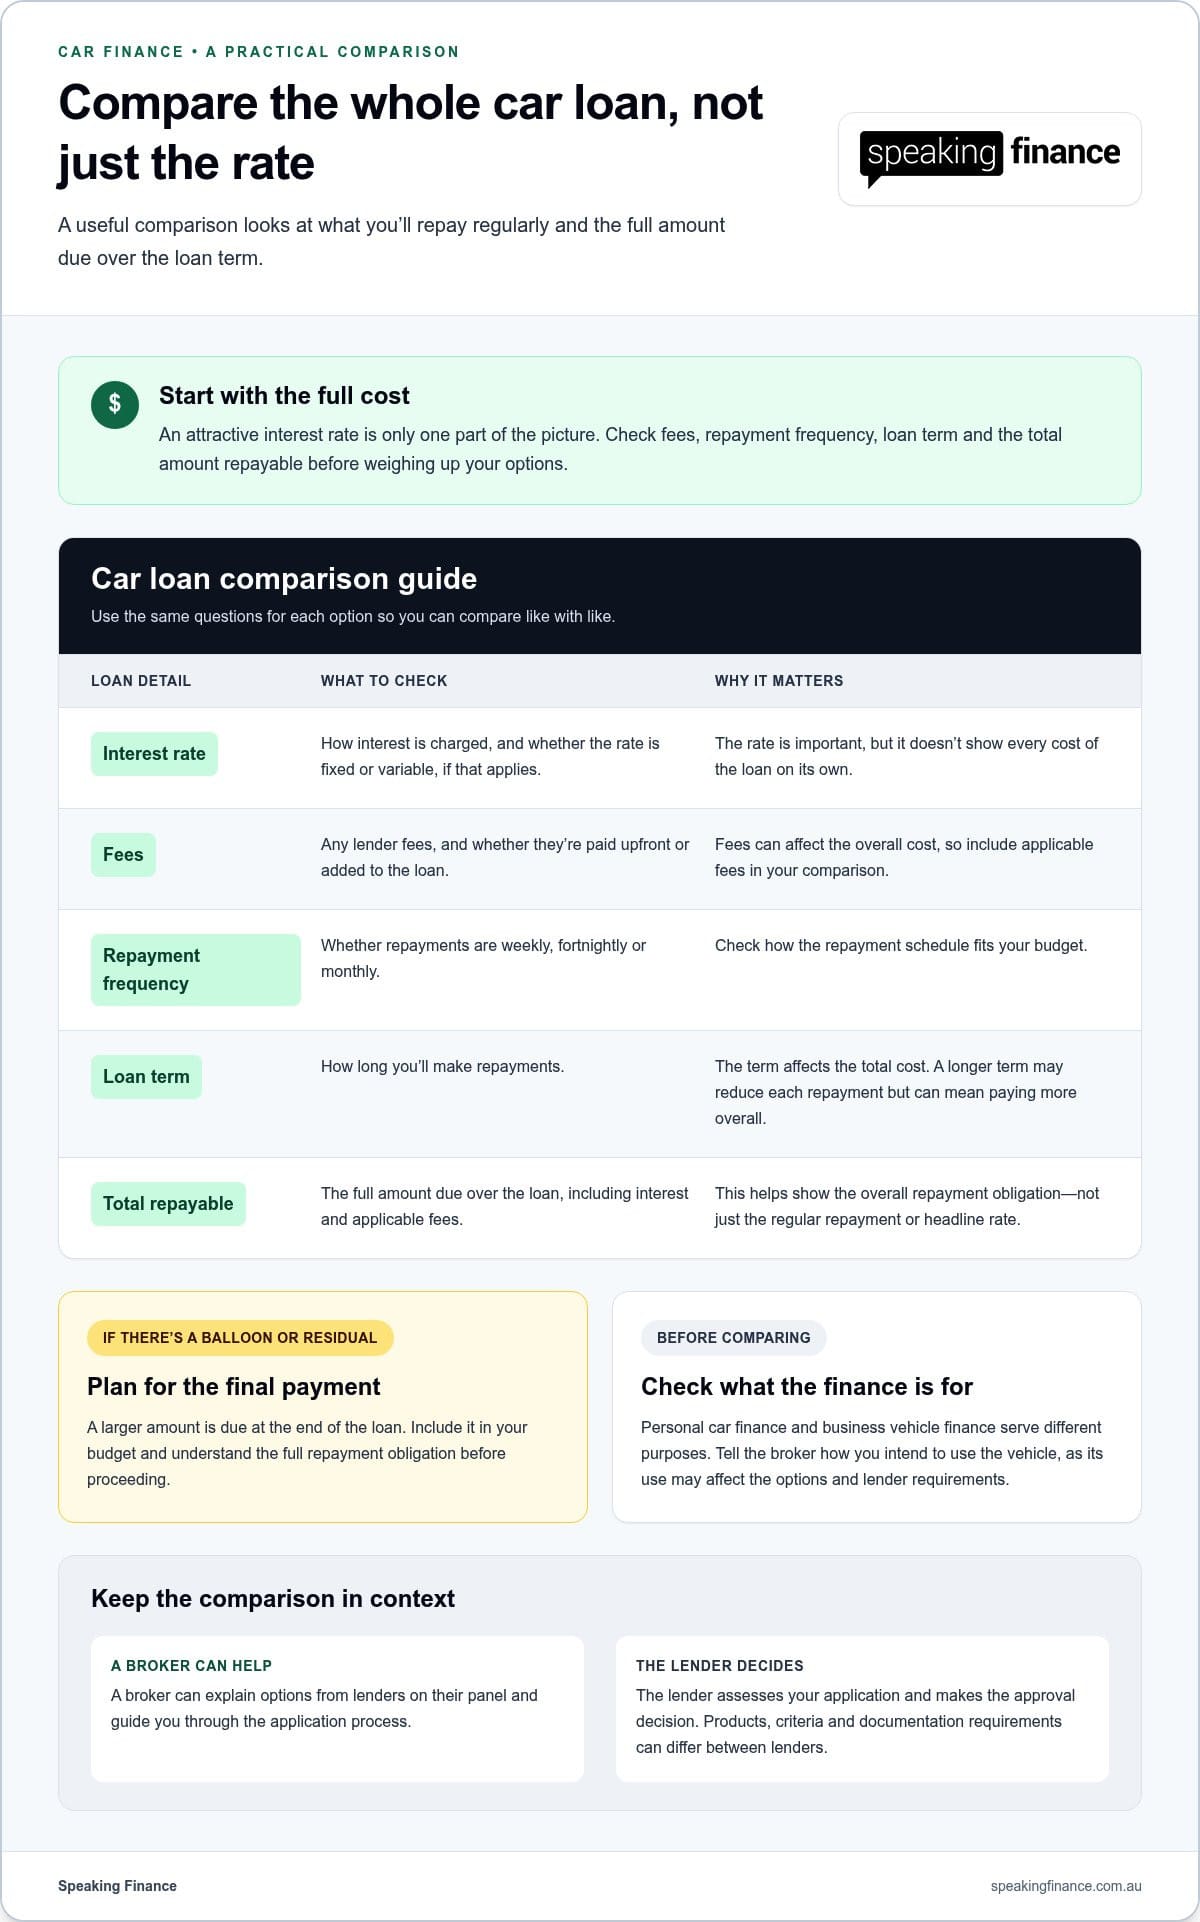
Look at the whole loan, not just one attractive number. Compare how each option affects your regular repayments and the total amount you’ll repay over the loan term.
| Loan detail | What to check |
|---|---|
| Interest rate | How interest is charged and whether the rate is fixed or variable, if that applies. |
| Fees | Any lender fees, and whether they’re paid upfront or added to the loan. |
| Repayment frequency | Whether repayments are weekly, fortnightly or monthly, and how they fit your budget. |
| Loan term | How long you’ll make repayments and how the term affects the total cost. |
| Total repayable | The full amount due over the loan, including interest and applicable fees. |
A longer term may reduce each repayment but can mean paying more overall. If the loan has a balloon or residual payment, a larger amount is due at the end. Include that amount in your budget and understand the full repayment obligation before proceeding. ABC News has reported on ASIC warnings on car finance in Australia, another reason to look beyond the headline rate and check the fees and terms carefully.
Does the car’s use affect finance options?
Yes. Personal borrowing and business vehicle finance serve different purposes. The vehicle’s details and intended use may affect which options and lender requirements apply. For a broader look at the types of finance buyers may consider, see Car finance options: A clear guide for buyers.
If you’d like help understanding options for your circumstances, see how we can help with car finance.
What should you ask about broker fees, commissions and approval?
Before proceeding, ask how the broker is paid and what costs may apply. A broker may earn a commission from a lender when a loan is completed, and payment arrangements can vary. A separate customer fee may also apply. Get a clear explanation so you understand the arrangement and any costs before moving ahead.
How can you understand a broker’s remuneration?
Ask direct questions, such as:
- How are you paid if I take out a loan?
- Could you receive a commission from the lender?
- Will I pay a separate broker fee, and when would it be payable?
- Are there lender fees or other costs I should understand?
Ask for the explanation in writing if that will make the details easier to review. A commission or fee doesn’t, by itself, tell you whether a loan is suitable or cheaper. Compare the full loan terms and costs, not just how the broker is paid. If terms such as “establishment fee” or “residual” are unfamiliar, Car finance terms explained in plain English can help clarify the language.
Can a broker guarantee your car loan approval?
No. A broker can help you explore options and prepare an application, but the lender assesses it and makes the lending decision. The outcome depends on the lender’s criteria, your application and your circumstances. A broker can’t guarantee approval, eligibility, a particular interest rate or savings.
That’s true whether you speak with a car finance broker Australia-wide or approach a lender directly. Broker support can help you understand the process, but it isn’t a promise of a particular result. Read the proposed terms carefully and make sure you understand the repayments and costs before agreeing to proceed.
How can you prepare to speak with a car finance broker?
A little preparation can make the first conversation more useful. You don’t need every document ready, but it helps to know what you’re looking for and what you want to ask.
What information can help start the conversation?
Use this simple sequence to get organised:
- Set a realistic budget: Consider what repayments could fit alongside your other expenses.
- Gather vehicle details: Note the make, model, year and price if you’ve chosen a car. If you’re still looking, say so.
- Think about timing: Be clear about when you hope to buy, without assuming finance will be approved by a particular date.
- Prepare questions: Ask about available options, repayments, fees, documents and what happens next.
You may also discuss your income, regular expenses and existing financial commitments. Be accurate and open about your circumstances. If you proceed, the lender may request supporting documents and will assess your application under its own criteria. Requirements can vary between lenders, so ask what information is needed for the option being considered.
How can Speaking Finance support the process?
Speaking Finance arranges car finance through a panel of more than 70 lenders. As a car finance broker Australia-wide, it can help you discuss options from its panel, understand the application steps and work through the information a lender may require. Speaking Finance isn’t the lender, and the lender makes the decision. Support through the process doesn’t guarantee approval, a particular rate or savings.
You can start with a conversation about your vehicle, budget and questions, then consider the options and next steps. The right type of finance depends on your circumstances, so one structure won’t suit everyone.
Make your next car finance conversation count
A car finance broker Australia buyers work with can explain available options and guide them through application steps, but the lender makes the lending decision. Before moving ahead, compare more than the headline rate: check fees, repayments, loan term and total amount repayable, and ask how the broker is paid.
A clear budget, vehicle details and a few questions can make it easier to discuss what may suit your circumstances. Speaking Finance arranges car finance through a panel of more than 70 lenders and can help you understand options and progress an application. The panel gives you options to discuss, not a promise of approval, a particular rate or savings.
Take the next step at your own pace, with a clearer picture of the questions to ask and costs to compare.
Frequently Asked Questions
What does a car finance broker do in Australia?
A car finance broker helps you explore and arrange finance through lenders. A car finance broker Australia-wide can discuss options from the lenders they work with, explain differences between loan terms and help you understand the application steps. Speaking Finance arranges car finance through a panel of more than 70 lenders. It isn’t a lender, so the lender assesses your application and makes the final decision.
Is it better to use a car finance broker or go directly to a lender?
Neither approach is automatically better for everyone. Going directly to a lender lets you discuss that lender’s products, while a broker may help you compare options across lenders on their panel. Consider how much guidance you want and compare the full loan terms, including fees, repayments and total repayable. A broker can explain options but can’t guarantee a lower cost or that a particular loan will suit you.
How does a car finance broker get paid?
A broker may earn a commission from a lender when a loan is completed. Payment arrangements can vary, and a broker may also charge the customer a separate fee. Ask how the broker is paid, whether you’ll pay any fees directly and what lender charges may apply. A clear explanation helps you understand the arrangement before deciding whether to proceed.
Can a car finance broker guarantee car loan approval?
No. A broker can help you explore finance options and prepare an application, but the lender assesses it and decides whether to approve the loan. The outcome depends on the lender’s criteria, your application and your circumstances. A broker can’t guarantee approval, eligibility, a particular interest rate or savings. Make sure you understand the terms being proposed.
What information should I prepare before speaking with a car finance broker?
Start with a realistic budget, details of the vehicle you’re considering and your intended purchase timing. Be ready to discuss your income, expenses and existing financial commitments, as these may help frame the conversation. Note any questions about repayments, fees, loan terms or next steps. If you proceed, the lender may ask for supporting documents, and its requirements can vary.
Article by
Steven Emms
Steven Emms is the Director of Speaking Finance, an Australian finance brokerage based in Melbourne, Victoria.
Steven and his team help consumers, sole traders and businesses navigate vehicle finance, equipment finance, business lending, working capital and personal finance. His approach is simple: explain finance in plain English, cut through unnecessary jargon and help clients make informed decisions.
At Speaking Finance, the philosophy is simple: **We make finance black and white.**
Outside of finance, Steven is a long-suffering Essendon supporter, which has given him plenty of practice managing expectations and dealing with disappointment.
Disclaimer
The information in this article is general in nature and is provided for educational purposes only. It does not take into account your personal circumstances, financial situation, needs or objectives and should not be relied upon as personalised financial or credit advice.
Speaking Finance is a finance brokerage, not a direct lender. Finance products, interest rates, fees, terms and eligibility criteria vary between lenders and are subject to individual assessment, applicable lending policies and approval. No finance approval or particular outcome is guaranteed.
Information is believed to be accurate at the time of publication but may change. Before making financial decisions, consider your circumstances and seek appropriate independent professional advice where necessary.