The loan that leaves your car out of the deal can cost more. When comparing a secured vs unsecured car loan, the key trade-off is often between using the car as security and keeping it outside the loan. But the label alone won’t tell you which option suits your circumstances or costs less overall.
It’s understandable to focus on the interest rate or wonder what happens if repayments become difficult. A secured loan uses the car as security, so the lender may have rights relating to the vehicle if you default, subject to the loan terms and applicable rules. An unsecured loan doesn’t use the car as security, but may have a higher rate or different conditions.
This guide explains how security can affect the risks and costs, and what to compare across offers, including the comparison rate, fees, repayment terms and early repayment conditions. You’ll also find practical questions to ask before applying, so you can weigh the full cost and consider how the loan could affect your plans for the car.
Key Takeaways
- When weighing a secured vs unsecured car loan, look beyond the label to how the agreement treats the car and missed repayments.
- Check the contract for conditions that could affect your use of the vehicle or your options later.
- Compare offers for the same borrowing amount and repayment period, then review the comparison rate, fees and total payable.
- A finance broker can help explain how lender policies and documentation requirements differ across potentially suitable options.
Secured vs unsecured car loan: what does the difference mean?
A secured loan uses an asset as security for the borrowing; an unsecured loan does not. With car finance, the asset may be the vehicle you’re buying. This describes how the loan is structured, not a guaranteed interest rate, approval or financial outcome. A secured loan may be priced differently from an unsecured one, but the actual offer depends on the lender, your circumstances and the contract.
The label is a starting point, not the whole story. Two loans described as secured can still have different conditions, fees and repayment arrangements. Read the agreement to see what is being used as security, what obligations apply and what may happen if you don’t meet them. The general idea behind a secured loan is straightforward, but the specific terms are set out in the loan documents.
What does it mean for a car loan to be secured?
If the vehicle is security, it acts as collateral under the loan agreement. The lender’s interest is connected to the car, rather than the loan relying only on your promise to repay. Check which vehicle the agreement covers and whether conditions apply to selling or changing it while the loan is outstanding. The contract, not the product label, spells out the arrangement.
What makes a car loan unsecured?
An unsecured car loan doesn’t offer the vehicle as security for that borrowing. That doesn’t make the loan a no-strings option: you still need to make repayments, and the lender’s terms and processes still apply if you fall behind. Read the agreement for the repayment schedule, fees and other conditions rather than assuming “unsecured” means fewer obligations or a better fit.
For personal borrowing, the finance is generally assessed as consumer car finance. If you’re financing a vehicle for business use, business vehicle finance may involve a different structure and documentation. Make sure you’re comparing like with like, and consider how each agreement fits the way you’ll use the car.
Secured vs unsecured car loans: weigh the trade-offs, not assumptions
The practical difference is what the agreement says about the vehicle if repayments fall behind. If the car secures the loan, the lender may have rights relating to it under the agreement. With an unsecured loan, the car isn’t offered as security, but you still owe the repayments and must follow the contract.
- Security: A secured loan names an asset, often the vehicle, as security. An unsecured loan doesn’t offer the car as collateral.
- Vehicle implications: Check whether the agreement sets conditions around selling, replacing or otherwise dealing with a car that secures the loan.
- Missed repayments: If you fall behind, the lender’s options may differ depending on the agreement and whether the vehicle is security. Don’t assume there are no consequences because the car isn’t collateral.
- Terms to clarify: Review the interest rate, comparison rate, fees, repayment conditions and any restrictions. These can vary by lender and applicant.
Neither structure is automatically more suitable for every borrower. Your circumstances and the full contract matter more than the label alone.
Does secured finance always mean a lower rate?
No. Security can affect how a lender assesses a loan, but it doesn’t guarantee a lower rate, approval or a better overall deal. Rates, fees, eligibility and conditions vary by lender and applicant. Compare the full offer, including fees and repayment terms, rather than choosing based on the security label or headline rate alone.
What should you understand about the collateral risk?
If you miss repayments on a secured loan, the lender may have rights relating to the vehicle under the agreement. The terms and process depend on the contract and circumstances, so read the relevant clauses before signing. If a payment becomes difficult, contact the lender promptly to discuss the situation rather than waiting for it to escalate.
Want help making sense of the differences? See how we can help compare car finance options and understand potentially suitable pathways.
How to compare secured and unsecured car loan offers
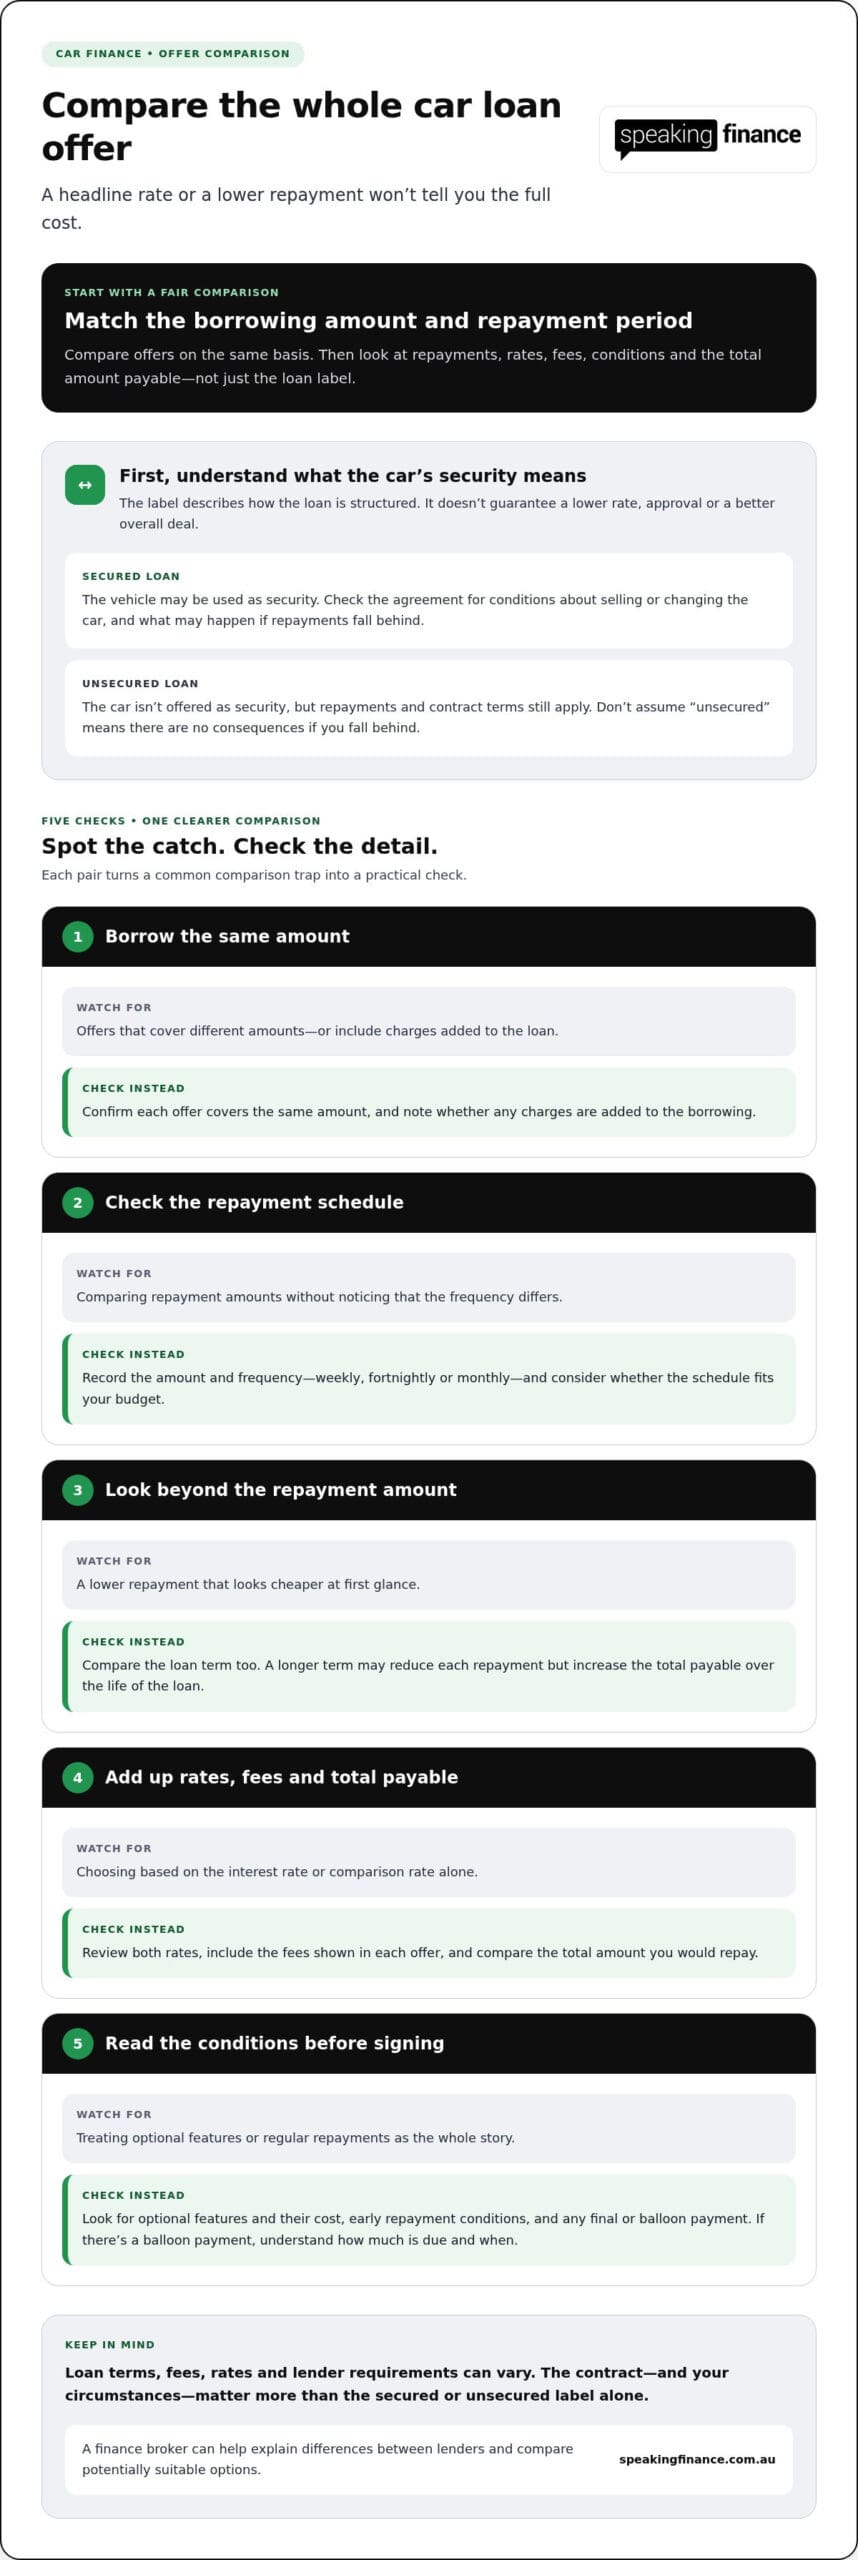
Put the offers side by side and compare the same borrowing amount and repayment period. A lower repayment can look appealing, but it may reflect a longer term or a final payment rather than a lower overall cost. Use this checklist to compare the whole offer, not just its headline rate.
- Match the amount borrowed. Check that each offer covers the same amount and note whether any charges are added to the loan.
- Compare repayments. Record the amount and frequency, such as weekly, fortnightly or monthly, and consider whether the schedule fits your budget.
- Check the loan term. A longer term may reduce each repayment but can increase the total payable over the life of the loan.
- Review rates, fees and total payable. Compare the interest rate and comparison rate, then include the fees shown in each offer. Check the total amount you would repay, not only the rate.
- Read the conditions. Look for optional features, early repayment conditions and any final or balloon payment. If there’s a balloon payment, understand how much is due and when.
Which loan details deserve a closer look?
Check whether you can make extra repayments or repay early, and whether conditions or charges apply. Compare optional features only if you need them, and include their cost in your assessment. If an offer includes a balloon payment, don’t treat the regular repayments as the full cost. For a broader overview of finance structures, see Car Finance Options in Australia: A Clear Guide for 2026.
How do your circumstances shape the comparison?
Think about your budget, how long you expect to keep the vehicle and how comfortable you are offering it as security. Suitability depends on your circumstances, lender criteria and contract terms. Use the written offers to see how each structure fits your plans, rather than deciding by the label alone.
Getting help to compare car finance options
A finance broker can help you understand potentially suitable pathways across a broad panel of lenders, rather than looking at only one lender’s offer. That can be useful if you’re weighing different finance structures or want help making sense of the requirements. Lenders can differ in their credit policies, documentation requirements and appetite for applications, so the options and information needed may vary.
What does a finance broker do during the process?
A broker starts by understanding your purpose, circumstances and objectives. They can then identify potentially suitable finance pathways and lenders, and explain key requirements and differences in plain English. If you decide to proceed, they collect and organise the information required for an application, present it to appropriate lenders, and manage communication, questions and document requests through the approval process.
A broker can also assist with documentation and settlement, and provide post-settlement support where relevant. This can make the steps clearer, but it’s still important to understand the lender’s offer and contract yourself.
What remains the lender’s decision?
The lender assesses the application and makes the credit decision. It also sets the final pricing and terms. A broker can explain options and help you compare offers, but can’t promise approval, a particular rate, timing or financial outcome. Any decision depends on your circumstances and the lender’s assessment.
The guide Car finance broker Australia: What to expect when you work with one in 2026 provides more background on the process. For a secured or unsecured loan, focus on how the proposed structure, requirements and terms fit your needs. Taking time to understand those differences can help you make a considered choice.
Choose the structure that fits your next steps
The right secured vs unsecured car loan choice should work not only for the purchase, but also for what you may want to do with the car later. Consider whether the agreement leaves room for your plans to change, especially if you might sell or replace the vehicle before the loan is paid off.
Before deciding, check that you understand the repayments, total cost and commitments you’re taking on. If the car is security, make sure you also understand the relevant conditions in the agreement.
Speaking Finance helps consumers compare car finance pathways across a broad panel of lenders and explains the differences in plain English. See how we can help.
Frequently Asked Questions
Can I sell a car while a secured car loan is still owing?
Possibly, but check the loan agreement and speak with the lender before arranging a sale. Ask how the outstanding balance would be handled and what steps are needed to release the vehicle from the loan security. The sale proceeds may not cover the amount still owing, so clarify how any shortfall would be dealt with before you commit to a sale.
Can I get a secured car loan for a used car?
A used car may be considered for secured finance, but lender criteria differ. The vehicle’s details and your circumstances can affect the options available, so don’t assume every used car will qualify for every loan. Gather accurate information about the car and compare the lender’s requirements with the offer’s full terms.
Does a secured car loan affect my credit score differently from an unsecured loan?
Not necessarily just because the loan is secured or unsecured. The effect on your credit file and score can depend on factors such as credit applications and repayment conduct, as well as how information is reported and assessed. If you’re comparing a secured vs unsecured car loan, focus on managing repayments and remember that a lender may consider your credit history as part of an application.
Can I change from an unsecured car loan to a secured one later?
You may be able to replace or refinance an unsecured loan with a secured option, but it won’t happen automatically. A lender would assess the new application and decide whether to offer finance against the vehicle. Before proceeding, compare the new loan’s total cost and conditions with your existing agreement, including any costs involved in paying out the current loan.
Article by
Steven Emms
Steven Emms is the Director of Speaking Finance, an Australian finance brokerage based in Melbourne, Victoria.
Steven and his team help consumers, sole traders and businesses navigate vehicle finance, equipment finance, business lending, working capital and personal finance. His approach is simple: explain finance in plain English, cut through unnecessary jargon and help clients make informed decisions.
At Speaking Finance, the philosophy is simple: **We make finance black and white.**
Outside of finance, Steven is a long-suffering Essendon supporter, which has given him plenty of practice managing expectations and dealing with disappointment.
Disclaimer
The information in this article is general in nature and is provided for educational purposes only. It does not take into account your personal circumstances, financial situation, needs or objectives and should not be relied upon as personalised financial or credit advice.
Speaking Finance is a finance brokerage, not a direct lender. Finance products, interest rates, fees, terms and eligibility criteria vary between lenders and are subject to individual assessment, applicable lending policies and approval. No finance approval or particular outcome is guaranteed.
Information is believed to be accurate at the time of publication but may change. Before making financial decisions, consider your circumstances and seek appropriate independent professional advice where necessary.