An affordable-looking repayment doesn’t always mean a good finance fit. A caravan finance broker can help you compare potential options from lenders, understand the trade-offs and prepare an application. The lender makes the credit decision and sets the final terms.
When planning a caravan purchase, it’s natural to focus on the repayment. But the interest rate, comparison rate, fees, loan term and any final repayment can all affect how an offer works for you. Lender requirements and repayment structures can also vary.
This guide explains what a broker does, what to compare and how to prepare for a useful conversation about your purchase and circumstances. No particular rate, approval or outcome is guaranteed.
Key Takeaways
- A caravan finance broker can help you explore lender pathways and compare their features. The lender decides whether to approve an application.
- Compare the repayment schedule and loan term, and check whether the proposal lists fees or a final repayment.
- Gather the caravan, seller and purchase details you have, and consider whether the caravan is for personal use, business use or both.
- Speaking Finance starts by understanding your objectives, then explores potential pathways and explains key differences in plain English.
When can a caravan finance broker help with your purchase?
A caravan finance broker can help you explore finance pathways and understand what information a lender may need. This can be useful when you’re weighing up a purchase and want to know which details could affect the finance structure or what to compare.
Speaking Finance is a brokerage, not a lender. Lenders can have different credit policies, documentation requirements and appetites, so an option that may suit one buyer or purchase won’t necessarily suit another. A broker can explain those differences and manage communication with a lender. The lender assesses the application and determines approval, pricing and final terms.
What does a caravan finance broker do?
A broker begins by discussing what you’re buying, how you plan to use it and your circumstances. A caravan for family holidays may raise different questions from one intended for business use. The broker can then explore potentially suitable options and present an application to a lender. Presenting an application is not the same as approving it: the lender assesses the details and decides whether to make an offer.
If you’re considering what to ask a broker, Choosing a finance broker: Questions to ask offers a related discussion.
Is caravan finance different from trailer finance?
They can be different purchase categories. A caravan is generally built as towable accommodation for travel, while “trailer” can describe a wider range of towable vehicles used to carry items or equipment. For a general overview, see Caravan (trailer).
The label alone doesn’t determine a finance pathway. The asset, its intended use and your circumstances may all matter, and lender requirements can vary. Speaking Finance also assists with trailer finance. For trailer-specific context, see Trailer Finance: Find an Option That Fits Your Purchase.
What should you compare in caravan finance options?
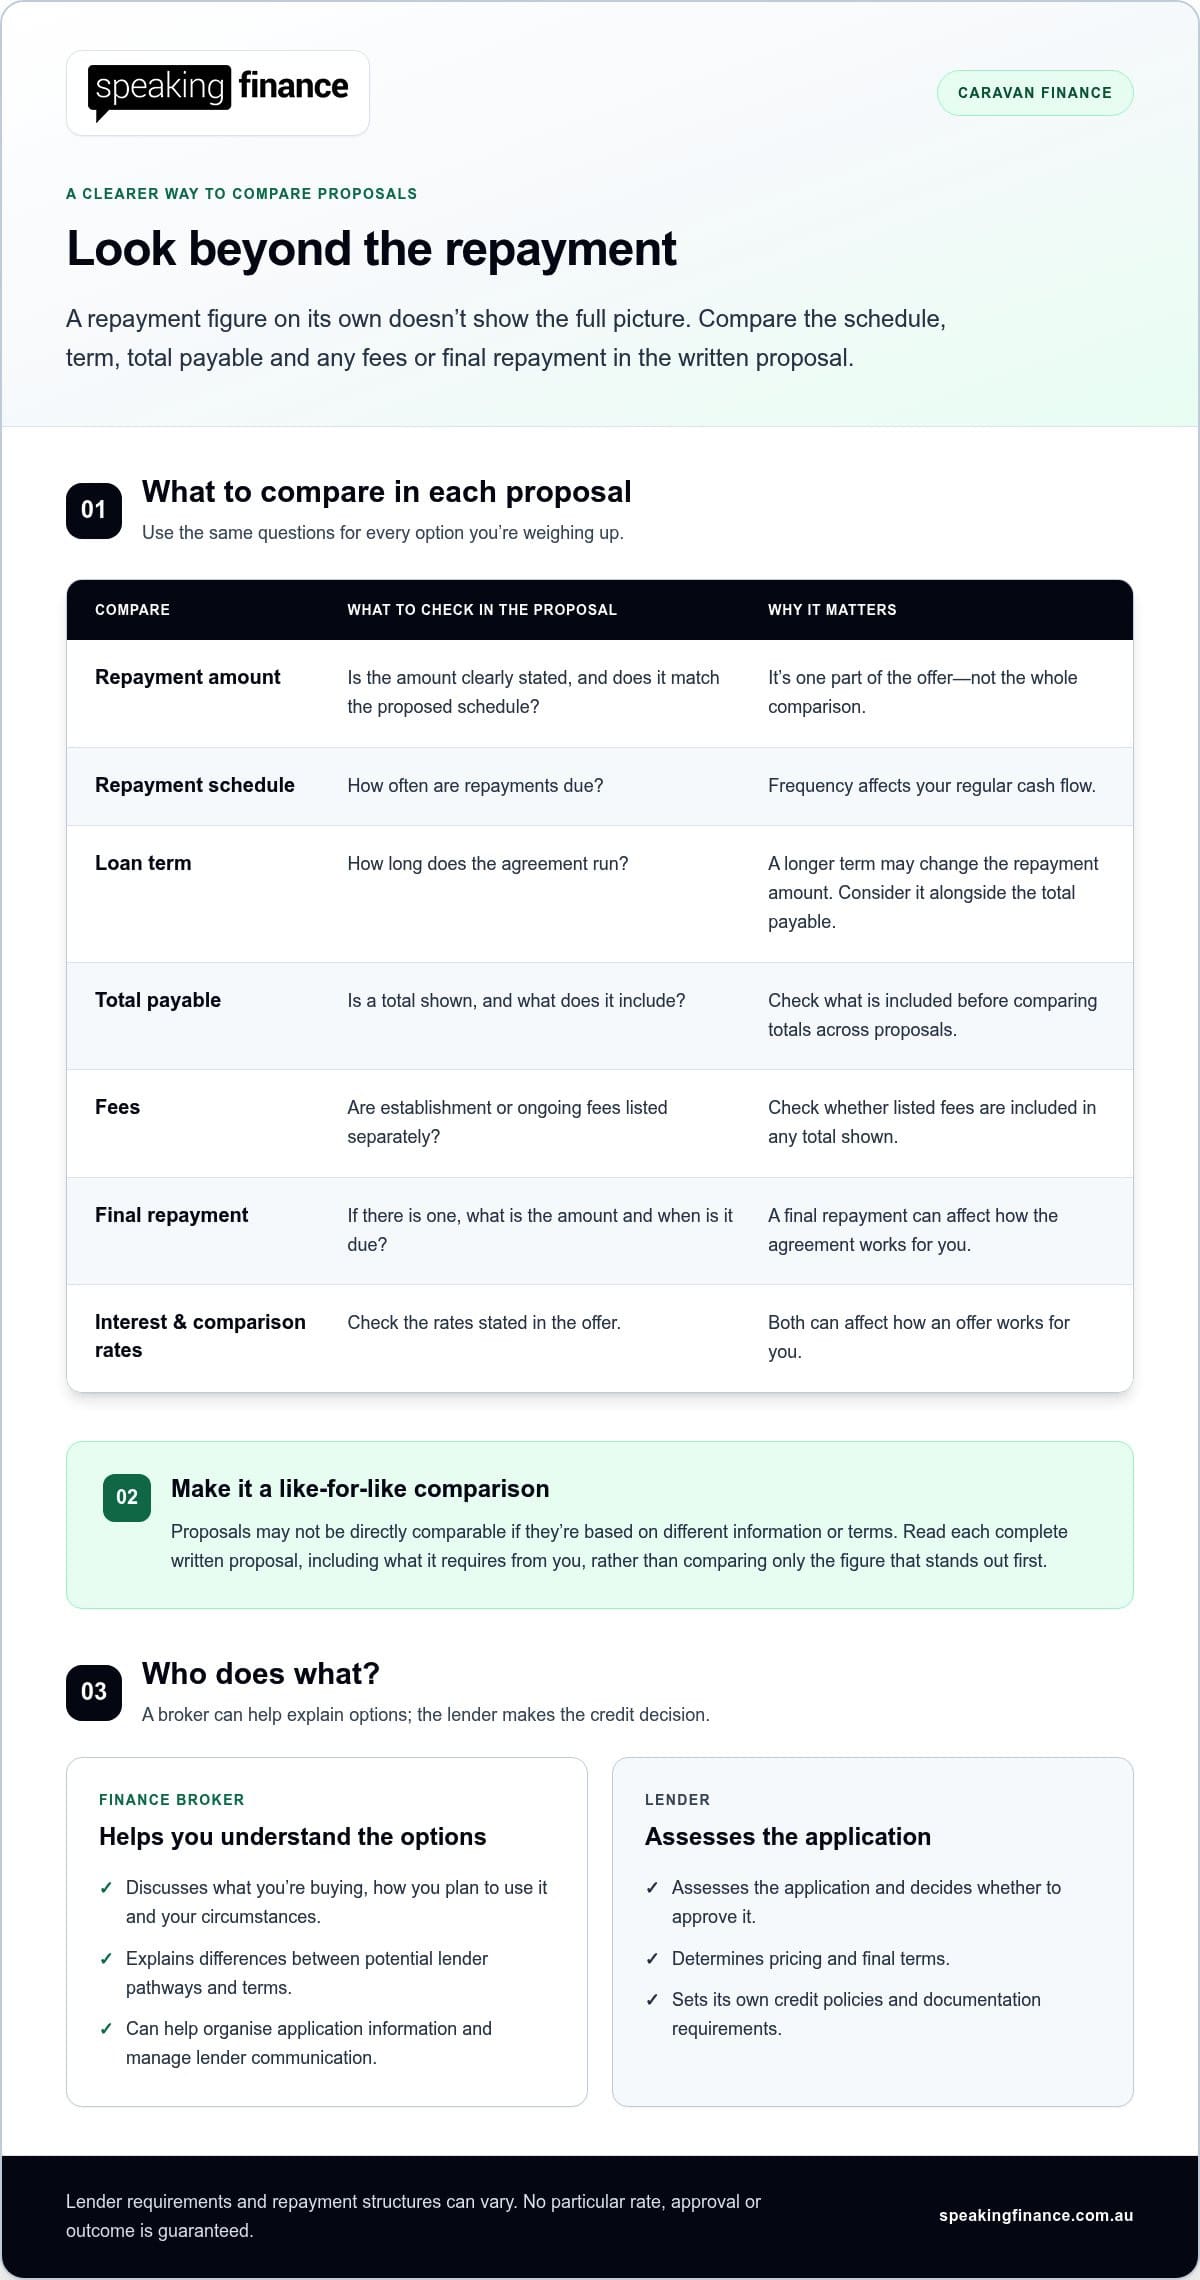
Look beyond the repayment amount. Compare how often repayments are due, the loan term, the total payable if shown, and any fees or final repayment listed in the lender’s written proposal. Put the full terms side by side rather than comparing only the figure that stands out first.
Which repayment details deserve a closer look?
Repayment frequency affects your regular cash flow, while the loan term tells you how long repayments continue. A longer term may change the repayment amount, so consider it alongside the total payable rather than on its own. If a proposal includes a final repayment, check its amount and due date. Look for establishment or ongoing fees too, and check whether they’re included in any total shown.
| What to compare | What to check in the proposal |
|---|---|
| Repayment amount | Is it clearly stated, and does it match the proposed schedule? |
| Repayment schedule | How often are repayments due? |
| Loan term | How long does the agreement run? |
| Total payable | Is a total shown, and what does it include? |
| Fees or final repayment | Are any listed separately or due at the end? |
How do lender requirements affect a comparison?
Lenders can differ in their credit policies, documentation requirements and available structures. Proposals may not be directly comparable if they’re based on different information or terms. Read each complete written proposal and check what it requires from you. A caravan finance broker can help explain the differences in plain English, without assuming one structure will suit every buyer.
If you’d like help understanding proposed terms, you can talk through your caravan finance options.
How can you prepare before discussing caravan finance?
You don’t need every purchase detail finalised before discussing finance. Notes about the caravan and how you plan to use it can make the conversation more focused and help identify what information may still be needed.
What purchase details should you have ready?
Gather what you already know. Some details can still be in progress.
- The caravan type and any details that help identify it.
- The seller’s name and contact details, if available.
- Purchase information, such as a quote, listing or sale details.
- Whether you’re considering personal use, business use or a mix of both.
Note any contribution you may have available and the repayment amount or schedule you’d feel comfortable discussing. These are useful starting points, not a promise about what a lender will offer or a recommendation about how much to borrow. If the caravan may be used for business, explain how you expect to use it rather than assuming a particular finance category will apply.
What information might a lender request?
Supporting documents depend on the lender’s requirements and your circumstances. A lender may ask for information to confirm your identity and understand your income. If the purchase relates to a business, it may also request relevant business information. There isn’t one fixed document checklist for every application.
Having relevant details to hand can make it easier to respond to requests, but there’s no need to guess which documents will be required. As the discussion progresses, note each request and clarify what the information is intended to show. This helps you organise what’s needed without gathering paperwork that may not be relevant.
What happens when you work with Speaking Finance on caravan finance?
Speaking Finance is an Australian finance brokerage that helps consumers and business clients understand caravan finance options. The process starts with your plans and circumstances, with potential pathways explained in plain English.
How does the broker support the application?
A caravan finance broker can help organise application information, explain document requests and manage communication with lenders. Speaking Finance works with a broad panel of lenders. The information and steps involved can vary depending on the lender, application and your circumstances.
The process follows these steps:
- Understand your purpose and objectives. Discuss what you’re buying, your circumstances and what you want the finance arrangement to do.
- Identify potential pathways and lenders. Explore options that may be relevant to your situation.
- Explain the key differences. Go through requirements and terms in plain English.
- Collect and organise application information. Gather the details required for an application.
- Present the application. Submit it to an appropriate lender or lenders for assessment.
- Manage communication and requests. Help with lender questions and requests for documents through the approval process.
- Assist through documentation and settlement. Provide support through these steps and post-settlement support where relevant.
The lender assesses the application and determines approval, pricing and final terms. Broker support can make the process easier to follow, but it can’t guarantee a particular outcome.
What is a sensible next step?
Use your purchase notes to explain what you’re considering and what you’d like clarified. If your plans change while you compare options, let your broker know. Keeping the discussion up to date helps ensure the information reflects the purchase you have in mind.
Take your next step with a clearer plan
Before proceeding, identify what you still want to understand, such as the repayment schedule, total payable or any final repayment. You can take time to review the proposed terms and consider how they fit your plans and circumstances.
If you’re still exploring or already have a caravan in mind, a conversation can help clarify the questions to resolve before an application is presented. See How We Can Help →
Frequently Asked Questions
Can I finance a used caravan?
Finance may be available for a used caravan, depending on the lender, the caravan and your circumstances. A caravan finance broker can help you understand which details may matter, such as the vehicle’s age, condition and purchase information. Share what you know, even if you’re still gathering details, so potential options can be discussed without assuming a lender will approve the application.
How much deposit do I need for caravan finance?
There isn’t one deposit amount that applies to every caravan finance application. Whether you need to contribute funds, and how much, can depend on the lender’s requirements, the purchase and your circumstances. If you have savings or a trade-in contribution in mind, mention it during the discussion. The lender can set out any required contribution in its proposed terms.
Can I apply for caravan finance if I am self-employed?
You can apply if you’re self-employed, but the lender will assess your application against its requirements. If your income comes from contracting or a business, you may be asked for relevant information to help show your financial position. What’s needed can vary, so explain how you earn your income and discuss document requests as they arise.
Can caravan finance be arranged for a private sale?
Finance may be possible for a caravan bought through a private sale, subject to the lender’s criteria and process. Be ready to provide the seller’s details and available information about the caravan and agreed sale. This can help clarify what the lender needs to assess the purchase. Finance isn’t confirmed until the lender has made its decision and provided its terms.
Article by
Steven Emms
Steven Emms is the Director of Speaking Finance, an Australian finance brokerage based in Melbourne, Victoria.
Steven and his team help consumers, sole traders and businesses navigate vehicle finance, equipment finance, business lending, working capital and personal finance. His approach is simple: explain finance in plain English, cut through unnecessary jargon and help clients make informed decisions.
At Speaking Finance, the philosophy is simple: **We make finance black and white.**
Outside of finance, Steven is a long-suffering Essendon supporter, which has given him plenty of practice managing expectations and dealing with disappointment.
Disclaimer
The information in this article is general in nature and is provided for educational purposes only. It does not take into account your personal circumstances, financial situation, needs or objectives and should not be relied upon as personalised financial or credit advice.
Speaking Finance is a finance brokerage, not a direct lender. Finance products, interest rates, fees, terms and eligibility criteria vary between lenders and are subject to individual assessment, applicable lending policies and approval. No finance approval or particular outcome is guaranteed.
Information is believed to be accurate at the time of publication but may change. Before making financial decisions, consider your circumstances and seek appropriate independent professional advice where necessary.