What if the first personal loan offer you see isn’t the only option worth considering? Comparing loan terms, lender requirements and fees can feel like a lot, especially when you’re unsure whether to start with a bank or a broker. A personal loan broker can help make the options easier to understand, but the lender still makes the final decision.
This guide explains what a broker does, how the process works and where a broker’s role ends. You’ll also learn what to compare, including the interest rate, comparison rate, fees and repayment terms, so you can look beyond the headline offer.
We’ll cover what to expect from an initial conversation, what information you may need for an application and how applying can affect your credit file. Whether you’re weighing up a broker or approaching a lender directly, you’ll come away with practical questions to help you decide what to do next.
Key Takeaways
- A personal loan broker can help you understand potential lending options, but the lender makes the credit decision.
- Start by clarifying what you need the loan for and your circumstances before considering possible pathways.
- Compare the full loan terms, repayment structure, fees and total amount repayable, not just the interest rate.
- Speaking Finance’s plain-English approach and broad lender access can help make lender requirements and next steps clearer.
What does a personal loan broker do, and how is that different from a lender?
A personal loan broker is an intermediary who helps you explore possible lending pathways. Rather than providing the loan, the broker considers your purpose and circumstances, then helps identify options from lenders they work with. A credit broker plays this connecting role between a borrower and lenders.
Speaking Finance is a brokerage, not a bank or direct lender. It can help you understand potential options and lender requirements, but the lender assesses your application and decides whether to approve it. The lender also sets the final rate, fees and loan terms, based on its policies and your circumstances.
Going directly to a lender means applying to that institution for one of its products. A broker may help you explore pathways across a broad panel of lenders. Different lenders can have different credit policies, documentation requirements and appetites, so comparing options can help you understand what each pathway involves. Access to multiple lenders doesn’t guarantee approval or a particular outcome.
What can a broker help you understand?
Lenders can differ in their credit policies and the documents they require. A broker can explain what information may be needed and help you consider potentially suitable options in light of your needs and circumstances. For example, if you’re borrowing for a specific personal expense, you can discuss which loan terms and costs to compare before deciding whether to apply.
How is a broker paid?
A brokerage may earn commission from a lender when a loan completes. The lender’s fees and loan terms are separate considerations, so review the costs shown for each loan option before deciding how to proceed.
How does the personal loan broker process work from first conversation to settlement?
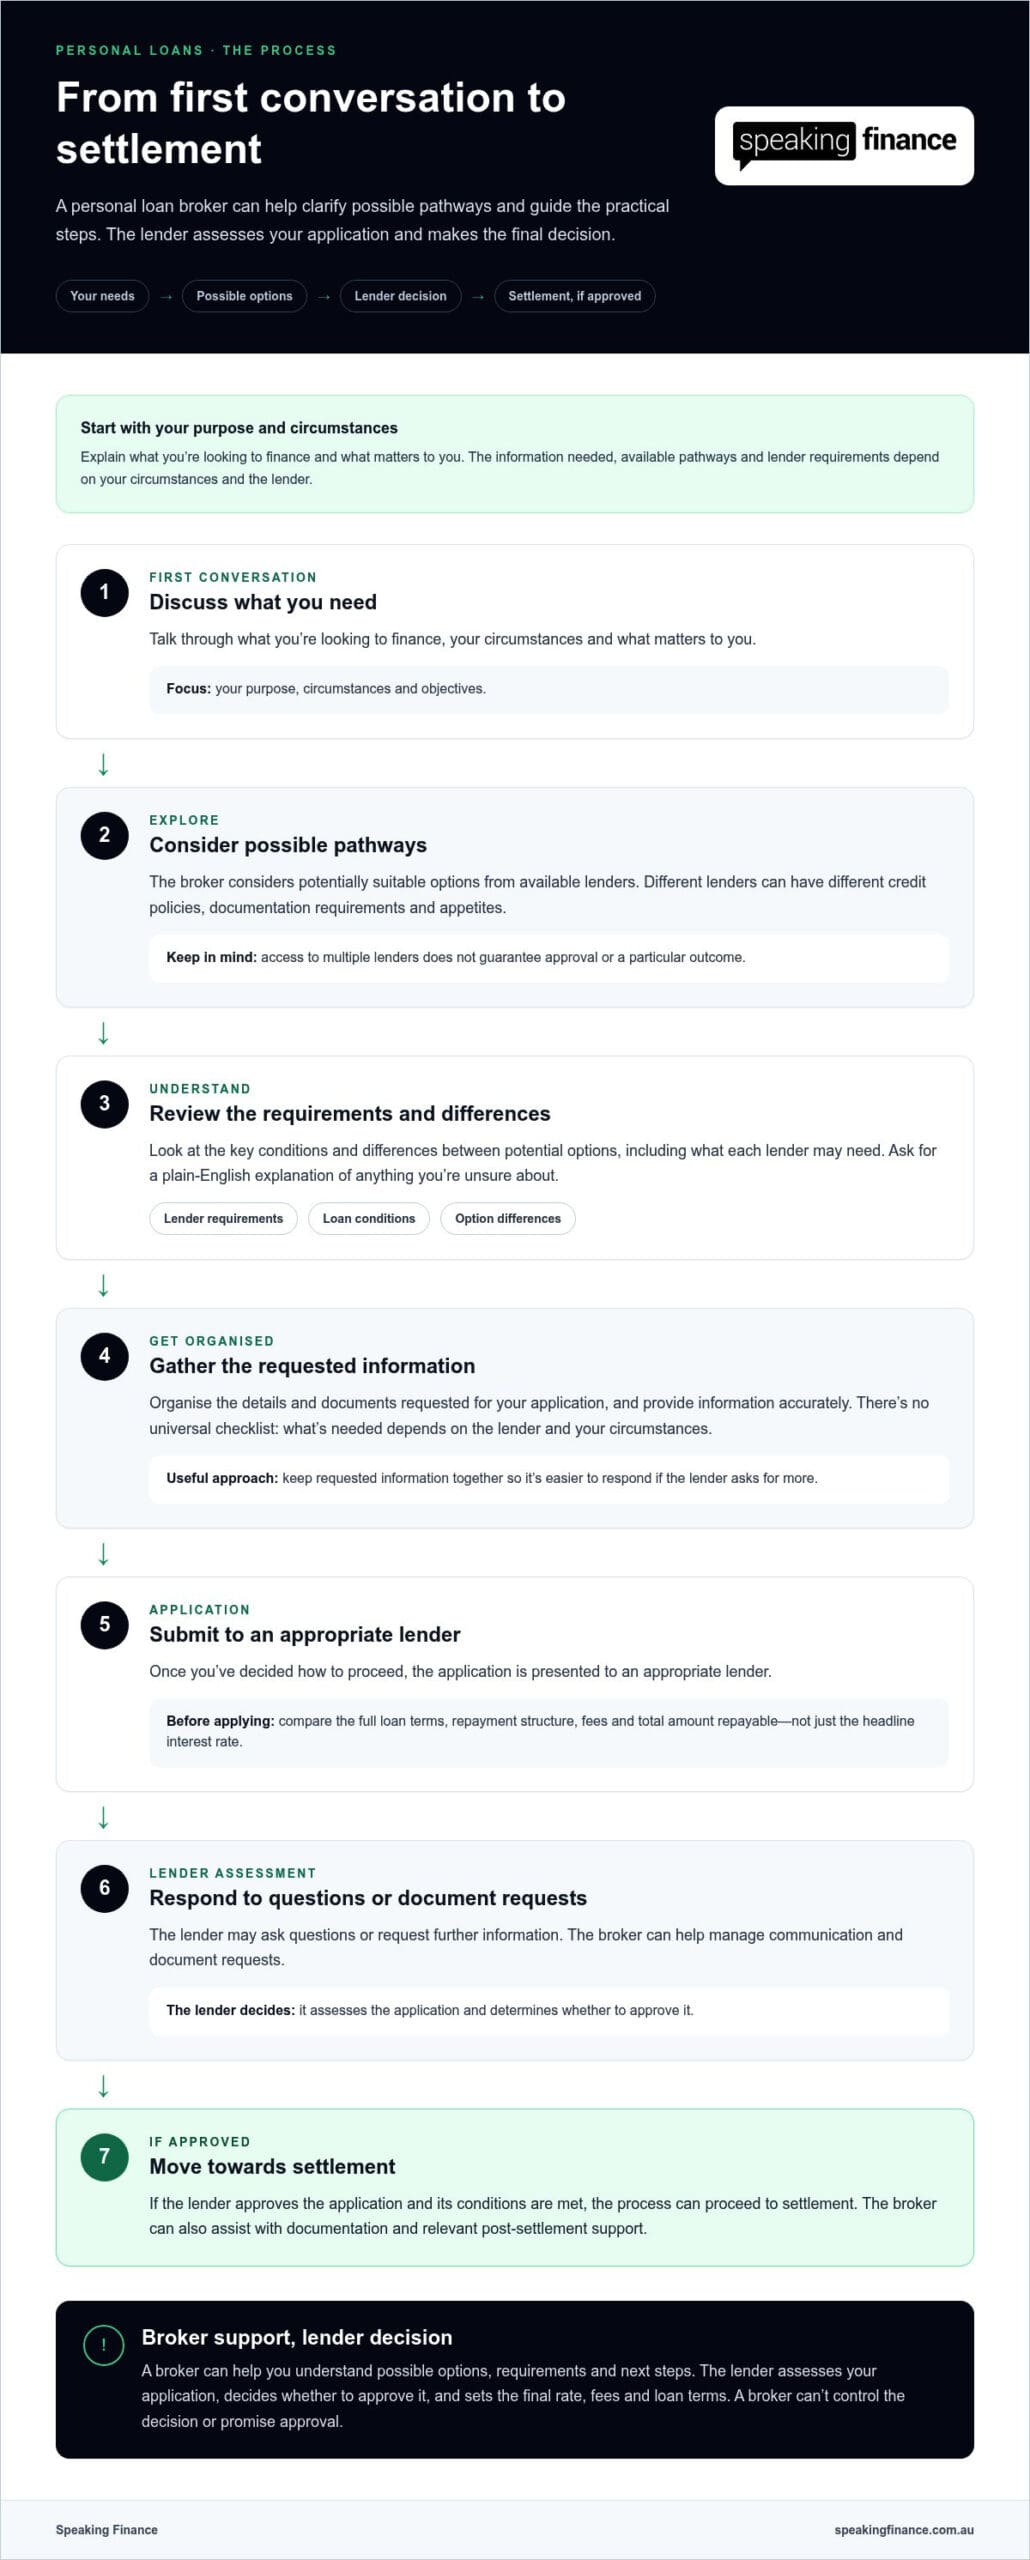
The process starts with your purpose, circumstances and objectives, not a product recommendation. From there, a personal loan broker can help clarify possible pathways and guide you through the practical steps. The information required depends on your circumstances and the lender’s requirements.
- Discuss your needs. Explain what you’re looking to finance, your circumstances and what matters to you.
- Explore possible pathways. The broker considers potentially suitable options from available lenders.
- Understand the requirements. Review the key conditions and differences between potential options, including what each lender may need, in plain English.
- Organise application information. Gather the details and documents requested for your application. Requirements vary, so there’s no universal checklist.
- Submit the application. Once you’ve decided how to proceed, the application is presented to an appropriate lender.
- Respond to lender requests. The lender may ask questions or request further information. The broker can help manage communication and document requests.
- Move towards settlement. If the lender approves the application and its conditions are met, the process can proceed to settlement. The broker can also assist with documentation and relevant post-settlement support.
Who makes the lending decision?
The lender assesses the application and decides whether to approve it. It also sets the pricing and final terms, which can vary between lenders and according to your circumstances. A broker can help you understand the process, but can’t control the decision or promise approval.
What information might you need to organise?
Keep requested information together and provide it accurately. What’s needed depends on the lender and your circumstances, so follow the requirements for your application rather than relying on a generic checklist. Your broker may help coordinate lender questions and follow-up requests. Keeping documents organised can make it easier to respond clearly if the lender asks for more information.
For an overview of the support Speaking Finance provides, see how we can help.
How should you compare personal loan options and broker support?
Compare each option against the reason you’re borrowing, your budget and your circumstances. Rates, fees, repayment structures and conditions vary by lender, so use current information for the specific loans being considered rather than relying on a general market figure. The lowest advertised rate alone won’t tell you what the loan may cost overall.
Which loan details deserve a closer look?
Check the repayment amount and schedule, then consider whether they fit your budget alongside your other commitments. Review the fees and conditions that apply, and compare the total amount repayable shown by the lender. A comparison rate combines the interest rate with most fees to help with like-for-like comparisons, but may not include every charge. Ask for a plain-English explanation of any term or condition you’re unsure about.
- Repayments: Check how often they’re due and whether the amount fits your budget.
- Costs and conditions: Review applicable fees and any terms that could affect how you use or repay the loan.
- Total cost: Compare the lender’s total repayment information, not just the headline rate.
A broker can also explain how potential options differ and what each lender may require. The right points to compare depend on the loan terms and your circumstances.
Could another finance category fit the purpose?
The purpose matters. Personal borrowing is different from finance arranged specifically for a vehicle or a business need. If you’re buying a car, explore car finance options as a separate category, then compare the relevant terms against your circumstances. If you’re considering debt consolidation, weigh the new loan’s costs and repayments against your existing commitments. Consolidating debts doesn’t automatically reduce the total cost, so compare the full figures before deciding.
What should you expect from a personal loan broker at Speaking Finance?
Expect a practical conversation, not a one-size-fits-all recommendation. Speaking Finance’s approach is simple: “We make finance black and white.” As a brokerage, it helps people explore personal loan options from a broad panel of lenders and understand what different pathways may involve. Different lenders can have different credit policies and documentation requirements, and access to a broad panel can help make those differences clearer. It can’t guarantee approval or a particular rate.
Speaking Finance assists with both consumer and business finance. For a personal loan enquiry, the focus is on personal borrowing and your reason for considering it. If you’re unsure whether your need is personal or business-related, explain the purpose so the relevant type of finance can be discussed.
What happens in an initial conversation?
The conversation starts with what you need the loan for, your circumstances and what you want to achieve. You can then discuss possible pathways and the requirements lenders may have, with unfamiliar terms explained in accessible language. This helps clarify potential next steps, but it doesn’t mean you’re eligible for a loan. The lender assesses your application and makes its own decision.
How can you take the next step?
You don’t need to arrive with every detail neatly filed. It can help to think about your priorities and prepare a few questions, such as:
- Which loan terms and repayment details should I compare?
- What information or documents might a lender request?
- What costs and conditions should I review?
These questions can help make the discussion useful and give you a clearer picture of what may happen next. Any options discussed are pathways to consider, not a promise of lending. The lender independently assesses your application and sets its final decision and terms.
Make your next borrowing decision with clarity
A useful next step is to turn what you’ve learned into a clear picture of your priorities. Before speaking with a personal loan broker, consider what the loan is for, what repayments could fit your budget and which terms you want explained. You don’t need to have every answer ready; knowing what matters to you is a good place to start.
Speaking Finance’s plain-English approach can help make finance easier to understand as you consider your next steps. Any lending decision remains yours to make, with the details in front of you.
Take your time, ask what you need to know and make your decision when the details are clear. A considered next step is better than feeling rushed into one.
Frequently Asked Questions
Is a personal loan broker a lender?
No. A personal loan broker helps explore lending options but doesn’t provide the loan funds. If a lender asks for more information after you apply, the broker may help you understand and respond to that request. The lender still assesses your application and decides whether to approve it. It also sets the final pricing and terms, so the broker can’t promise a particular result.
Can a personal loan broker help compare lenders?
Yes. A personal loan broker may help you compare possible options and understand differences in lender requirements. For example, if two options have different repayment schedules or documentation requirements, you can discuss what those differences mean for your circumstances. The options depend on your situation and the lenders’ current criteria. Review the terms and costs supplied for each option before deciding whether to apply.
How does a personal loan broker get paid in Australia?
A brokerage may receive commission from a lender when a loan is completed. Review the loan information provided so you understand the lender’s fees and terms before deciding whether to proceed.
Does speaking with a personal loan broker affect your credit file?
An initial conversation isn’t the same as lodging a loan application, but credit-file activity depends on what checks are carried out and whether an application is submitted. Before authorising a check, ask what type it is, who will conduct it and whether it may be recorded on your file. Make sure you understand the proposed steps before giving permission to proceed.
Can a personal loan broker guarantee loan approval?
No. A broker can’t guarantee approval, a specific rate or particular loan terms. If a broker helps prepare an application, the lender still reviews it against its own policies and your circumstances. You can use a conversation with a broker to understand possible pathways and what information may be needed, but treat any outcome as undecided until the lender has assessed the application.
Article by
Steven Emms
Steven Emms is the Director of Speaking Finance, an Australian finance brokerage based in Melbourne, Victoria.
Steven and his team help consumers, sole traders and businesses navigate vehicle finance, equipment finance, business lending, working capital and personal finance. His approach is simple: explain finance in plain English, cut through unnecessary jargon and help clients make informed decisions.
At Speaking Finance, the philosophy is simple: **We make finance black and white.**
Outside of finance, Steven is a long-suffering Essendon supporter, which has given him plenty of practice managing expectations and dealing with disappointment.
Disclaimer
The information in this article is general in nature and is provided for educational purposes only. It does not take into account your personal circumstances, financial situation, needs or objectives and should not be relied upon as personalised financial or credit advice.
Speaking Finance is a finance brokerage, not a direct lender. Finance products, interest rates, fees, terms and eligibility criteria vary between lenders and are subject to individual assessment, applicable lending policies and approval. No finance approval or particular outcome is guaranteed.
Information is believed to be accurate at the time of publication but may change. Before making financial decisions, consider your circumstances and seek appropriate independent professional advice where necessary.