The finance option that looks simplest may not be the right fit for your caravan or budget. Caravan finance Australia can involve different loan structures, so look beyond the regular repayment and consider how the finance fits the purchase and your plans for the caravan.
Comparing lender requirements can feel confusing when you’re also weighing repayments against your other commitments. This guide explains key considerations, including personal and business finance, secured and unsecured loans, fixed and variable rates, and balloon payments. You’ll also find practical details to compare and organise before an application. Speaking Finance is a finance brokerage, not a lender. It can help you understand potentially suitable pathways from a broad panel of lenders. The lender assesses each application and sets any final terms.
Key Takeaways
- Match the finance discussion to how you’ll use the caravan, rather than assuming one option suits every purchase.
- When comparing caravan finance Australia options, consider whether the purchase is personal or business-related and how the finance structures differ.
- Prepare by clarifying the purchase, reviewing your finances and gathering relevant records. Requirements vary by lender and application.
- A broker can explain potential pathways and lender requirements, while the lender makes the final decision and sets the terms.
Caravan finance in Australia: what to understand before you buy
Caravan finance is funding arranged to help pay for a caravan. The available options, assessment process and final terms depend on the lender and your circumstances. Start by getting clear on what you’re buying, how you plan to use it and what repayments may fit alongside your other commitments.
There’s no single structure that suits every buyer. First clarify the purchase and your plans, then consider the finance questions that follow. This guide covers general finance considerations, not personal financial or tax advice. If you’re weighing tax treatment for business use, speak with a qualified tax professional.
What details shape a caravan finance discussion?
The discussion usually starts with your objective: what you plan to buy, whether it’s for personal or business use, and what you want the finance to achieve. Your financial circumstances and repayment capacity also help frame the conversation. These details don’t guarantee an outcome, but they help identify which questions and potential pathways may be relevant.
A caravan for family holidays is a personal purchase. One acquired for genuine business use raises different considerations, including how it will be used and accounted for. Calling a purchase a business expense doesn’t automatically make it business finance. The purpose and circumstances matter.
Why the caravan and its intended use matter
Be ready to describe the caravan you’re considering and how you expect to use it. Is it a towable caravan for holidays, or an asset connected to business activity? The type of asset and its intended use give context to a finance enquiry. Lenders can assess assets and applicants under different policies, so a pathway available for one purchase may not suit another.
The purchase price is only part of the decision. Consider repayments alongside your regular expenses and other commitments, and think about how long you expect to keep the caravan. Clear details give you a more useful starting point for exploring caravan finance Australia without assuming approval or particular terms.
Caravan finance options: compare the purpose and structure
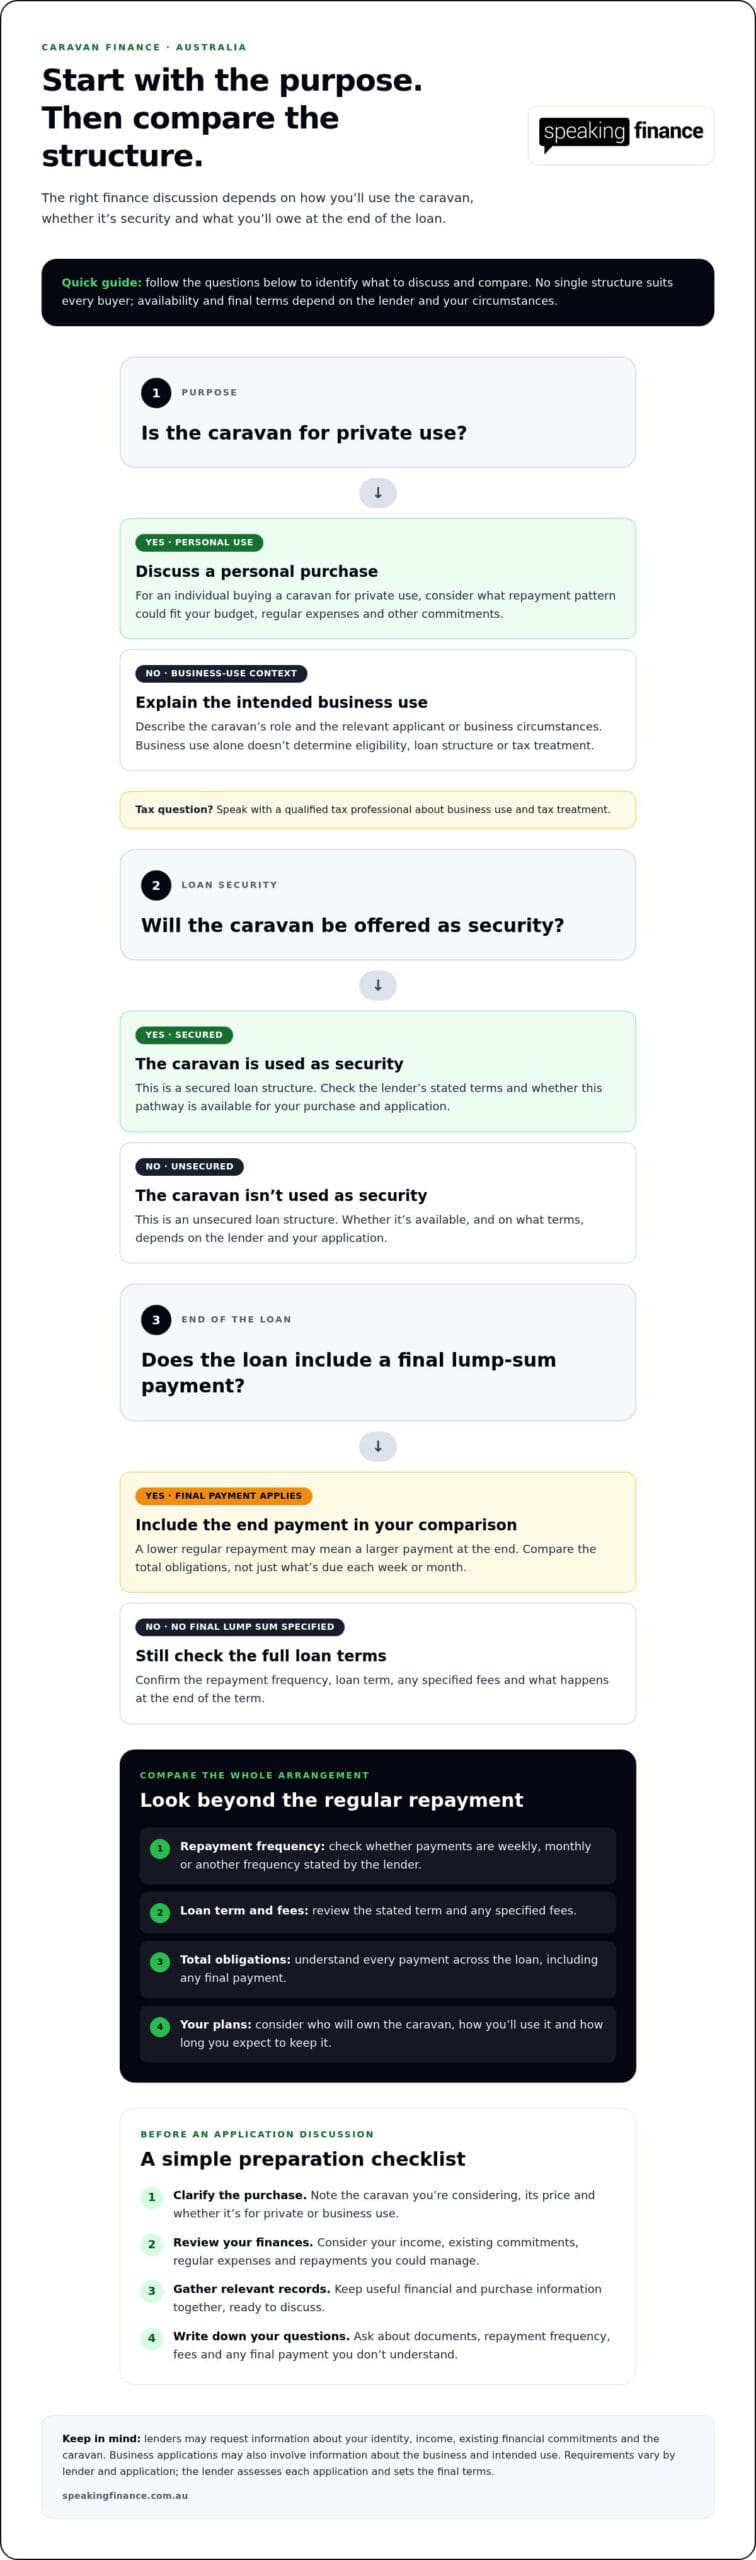
Caravan finance options can differ in purpose and structure. Personal finance generally relates to an individual purchase, while business finance is considered in the context of business use and circumstances. A secured loan uses the caravan as security; an unsecured loan doesn’t. Whether either pathway is available, and on what terms, depends on the lender and your application.
Compare the whole arrangement, not just the regular repayment. Consider who will own the caravan, how it will be used, your other financial commitments and whether the loan includes a final payment or another end-of-term obligation. The Caravan Industry Association of Australia provides information about the caravan and RV sector that may help with broader purchase research.
Personal or business caravan finance: what is different?
A personal finance enquiry focuses on an individual buying a caravan for private use. A commercial enquiry considers the purchase in a business context, including its intended role and the applicant’s circumstances. Business use alone doesn’t determine eligibility, the loan structure or tax treatment. If you have tax questions, get advice from a qualified tax professional.
Which finance details should you compare?
Review the lender’s stated terms side by side. Check the repayment frequency, loan term, any specified fees and whether a final lump-sum payment applies. A lower regular repayment may mean a larger payment at the end, so compare the total obligations across the loan, not just the amount due each week or month. Make sure you understand what happens at the end of the term. Related asset finance considerations may also apply to other towable purchases, such as those discussed in Trailer Finance: Find an Option That Fits Your Purchase.
- Personal purchase: Is the caravan for private use, and what repayment pattern could fit your budget?
- Business purchase: How will the caravan be used, and what applicant or business details may need to be discussed?
- Secured or unsecured: Is the caravan offered as security, and what terms does the lender specify?
If you want help understanding potentially suitable pathways, see how Speaking Finance can help.
Preparing a caravan finance application: details to organise
Some preparation can make a caravan finance discussion clearer. Start with the purchase, take stock of your finances and gather relevant records. This helps keep the conversation focused, but it doesn’t guarantee an outcome. The lender assesses each application, and requirements vary.
- Clarify the purchase. Note the caravan you’re considering, its price and whether the purchase is personal or for business use.
- Review your finances. Consider your income, existing commitments and the repayments you could manage alongside regular expenses.
- Gather relevant records. Keep useful financial and purchase information together, ready to discuss.
- Write down your questions. Ask about anything you don’t understand, including required documents, repayment frequency and any final payment.
What information might a lender request?
Depending on the application, a lender may ask about your identity, income, existing financial commitments and the caravan. For a business purchase, the lender may also seek information relevant to the business and intended use. These are examples, not a universal checklist. Documentation and assessment requirements differ between lenders and depend on the applicant and finance pathway.
Provide accurate, consistent details. If something has changed or needs explaining, mention it rather than leaving a gap that could lead to questions later.
How to prepare before discussing finance
Before discussing caravan finance Australia, jot down the purchase purpose, your working budget and your preferred repayment approach. You could also gather relevant records, such as income information, details of regular commitments and information about the caravan purchase. The exact documents needed depend on your circumstances and the lender, so treat this as a starting point rather than a fixed application checklist.
Clear information helps a broker explain potential pathways and what a lender may need to assess them. The lender makes the credit decision and sets any final terms. Approval and a particular timeframe can’t be promised.
How a caravan finance broker can support your next steps
A finance broker can help make the application process easier to follow, from identifying potential pathways to organising lender communication. Speaking Finance works with a broad panel of lenders. Their policies, documentation requirements and appetite for different applications can vary. The lender assesses the application and determines any final terms.
What happens when you speak with Speaking Finance?
The process starts with understanding your purchase plans, intended use, circumstances and objectives. Speaking Finance can then identify potentially suitable finance pathways and lenders, and explain key requirements and differences in plain English. If you decide to proceed, the team can collect and organise information for an application, present it to an appropriate lender, and manage communication, questions and document requests through the approval process. It can also assist with documentation and settlement, with post-settlement support where relevant.
This support can help you understand what’s being requested and what may happen next. You can also explore the finance services available through Speaking Finance.
Discuss your caravan finance questions
Bring the details you have about the caravan and how you plan to use it, along with any questions about the application process. If your plans are still taking shape, say so. A clear discussion can help identify what information may be useful and which points need further consideration, without assuming a lender will approve the application.
Take the time you need to understand the options and decide what fits your circumstances.
Take the next step with a clear picture
A caravan purchase is easier to assess when you’ve considered how the commitment fits your plans beyond the excitement of the first trip. Before moving ahead with caravan finance Australia, weigh the ongoing repayments, any final payment and the other costs that come with owning a caravan. Note any questions you still want answered.
You don’t have to settle every detail at once. A useful next step can be reviewing your plans and deciding what you’d like to clarify.
When you’re ready, see how we can help.
Frequently Asked Questions
Can I get finance for a new or used caravan?
Finance may be available for a new or used caravan, depending on the lender, the caravan and your application. For a used model, have details such as the make, year, condition and sale information ready. These help clarify what’s being purchased, but don’t determine the outcome on their own. A broker can help discuss potentially suitable lender pathways.
How much deposit do I need for caravan finance?
Deposit requirements for caravan finance Australia buyers can vary by lender, finance option and individual circumstances. There isn’t one amount that applies to every purchase. If you have savings to contribute, note how much you’re comfortable putting towards the caravan and discuss how that could affect the amount you want to borrow. The lender determines any deposit requirement and final terms.
Can I use business finance to buy a caravan?
Business finance may be considered where the purchase relates to business use, but using a caravan for work doesn’t automatically determine the finance structure or eligibility. Be ready to explain how it will be used and who will own it. If you’re considering claiming business expenses or depreciation, ask a registered tax agent for advice, as tax treatment depends on your circumstances.
What documents are needed to apply for caravan finance?
The documents requested depend on the lender, your circumstances and the finance pathway. For example, an employee may be asked for income evidence, while a self-employed applicant may need to provide business information. Details about the caravan, such as a quote or sale paperwork, may also be relevant. These are possible examples, not a standard checklist for every application.
Does caravan finance guarantee approval once I apply?
No. Submitting an application doesn’t guarantee approval. The lender assesses the information provided and makes its own decision. It may ask for further details before deciding, and if the application is approved, the lender sets the final terms. A finance broker can help present information and manage lender questions, but can’t promise approval, a rate or any other outcome.
Article by
Steven Emms
Steven Emms is the Director of Speaking Finance, an Australian finance brokerage based in Melbourne, Victoria.
Steven and his team help consumers, sole traders and businesses navigate vehicle finance, equipment finance, business lending, working capital and personal finance. His approach is simple: explain finance in plain English, cut through unnecessary jargon and help clients make informed decisions.
At Speaking Finance, the philosophy is simple: **We make finance black and white.**
Outside of finance, Steven is a long-suffering Essendon supporter, which has given him plenty of practice managing expectations and dealing with disappointment.
Disclaimer
The information in this article is general in nature and is provided for educational purposes only. It does not take into account your personal circumstances, financial situation, needs or objectives and should not be relied upon as personalised financial or credit advice.
Speaking Finance is a finance brokerage, not a direct lender. Finance products, interest rates, fees, terms and eligibility criteria vary between lenders and are subject to individual assessment, applicable lending policies and approval. No finance approval or particular outcome is guaranteed.
Information is believed to be accurate at the time of publication but may change. Before making financial decisions, consider your circumstances and seek appropriate independent professional advice where necessary.