The headline rate alone won’t tell you whether a marine loan suits your boat purchase. Marine loans can be structured differently depending on the vessel, whether you’re buying personally or for a business, and how you need repayments to work. Check the full terms against your circumstances before you apply.
Compare more than the interest rate. The security arrangement, fees, repayment frequency, loan term and lender requirements can all affect the cost and structure of finance. A boat’s age, the purchase details and whether you’re buying privately or through a dealer may also be relevant. Secured and unsecured finance work differently, so make sure you understand what the lender is offering.
This guide explains common marine finance pathways, what to check when comparing loan terms and which questions to ask before applying. It also outlines how a broker can explain differences between lender requirements and help you consider potentially suitable options in plain English.
Key Takeaways
- Marine loans can fund a vessel purchase, but the lender assesses the vessel, purpose and proposed structure.
- Personal lending and business asset finance have different considerations. Compare how each option handles security, repayments and the loan term.
- Before applying, define what you’re buying, consider the effect on your budget or business cash flow, and review the written loan terms.
- A broker can explain lender requirements and potentially suitable pathways. The lender makes the credit decision.
What can marine loans cover, and who might consider them?
Marine finance can help fund a vessel purchase, subject to the lender’s assessment. Lenders may differ in the vessels, purchase purposes and loan structures they consider. Start by identifying what you plan to buy, who will own it and how it will be used. A recreational boat for personal use may lead to different finance pathways from a vessel acquired for a business.
Marine loans can also involve different security arrangements. You might come across the term ship mortgage, which describes a form of security associated with ships. It doesn’t mean every recreational boat loan uses that structure. Read the specific finance terms rather than assuming the label explains the whole arrangement.
Is the boat for personal or business use?
Purpose matters because personal consumer finance and business finance are assessed through different pathways. If you’re buying a boat for personal use, a personal finance option may be relevant to explore. If a business will use the vessel, the lender may consider the business purpose and its circumstances as part of the application. Intended use, ownership and the applicant’s financial position can all affect which options are considered.
For example, a vessel used in a business may need to be considered alongside the business’s cash flow and existing commitments. A personal purchase is assessed in the context of the individual applicant. These are useful starting points for a comparison, not confirmation of eligibility or approval. Lender requirements and available structures vary.
Speaking Finance arranges marine finance and can explain relevant business loan options alongside marine finance pathways for a business purchase. Be clear about who is buying the vessel and what it will be used for. That makes it easier to identify the questions to resolve before applying.
How do marine loan structures differ?
Marine finance may be considered through personal lending or business asset finance. The purchase, how the vessel will be used and the lender’s assessment all influence which pathways may be available. Security, loan term and repayment arrangements can vary, so compare the written terms rather than relying on a product label.
| What to compare | Personal lending | Business asset finance |
|---|---|---|
| Purpose | A personal vessel purchase | A vessel acquired for business use |
| Assessment | The applicant’s circumstances and the lender’s criteria | The business purpose and relevant applicant or business circumstances |
| Terms | Security, term and repayments set out in the offer | Security, term and repayments set out in the offer |
What does secured finance mean for a boat purchase?
With secured finance, an asset or another obligation is named as security under the lender’s terms. Don’t assume the boat is automatically the security. Check the offer documents to see exactly what is used as security and what the agreement says about your responsibilities. The arrangement depends on the lender and the application.
Which finance details should you compare?
Review the full repayment structure, not just the scheduled payment. Check the interest rate, applicable fees, repayment frequency and loan term, and whether an end-of-term amount is due. Compare the total amount payable shown in each offer. A smaller regular repayment on its own doesn’t mean the finance will cost less overall.
Use the lender’s written offer documents for a like-for-like comparison. If a term or condition is unclear, get it explained before proceeding. Speaking Finance can help explain differences between potentially suitable marine loan options.
How can you compare marine loans before applying?
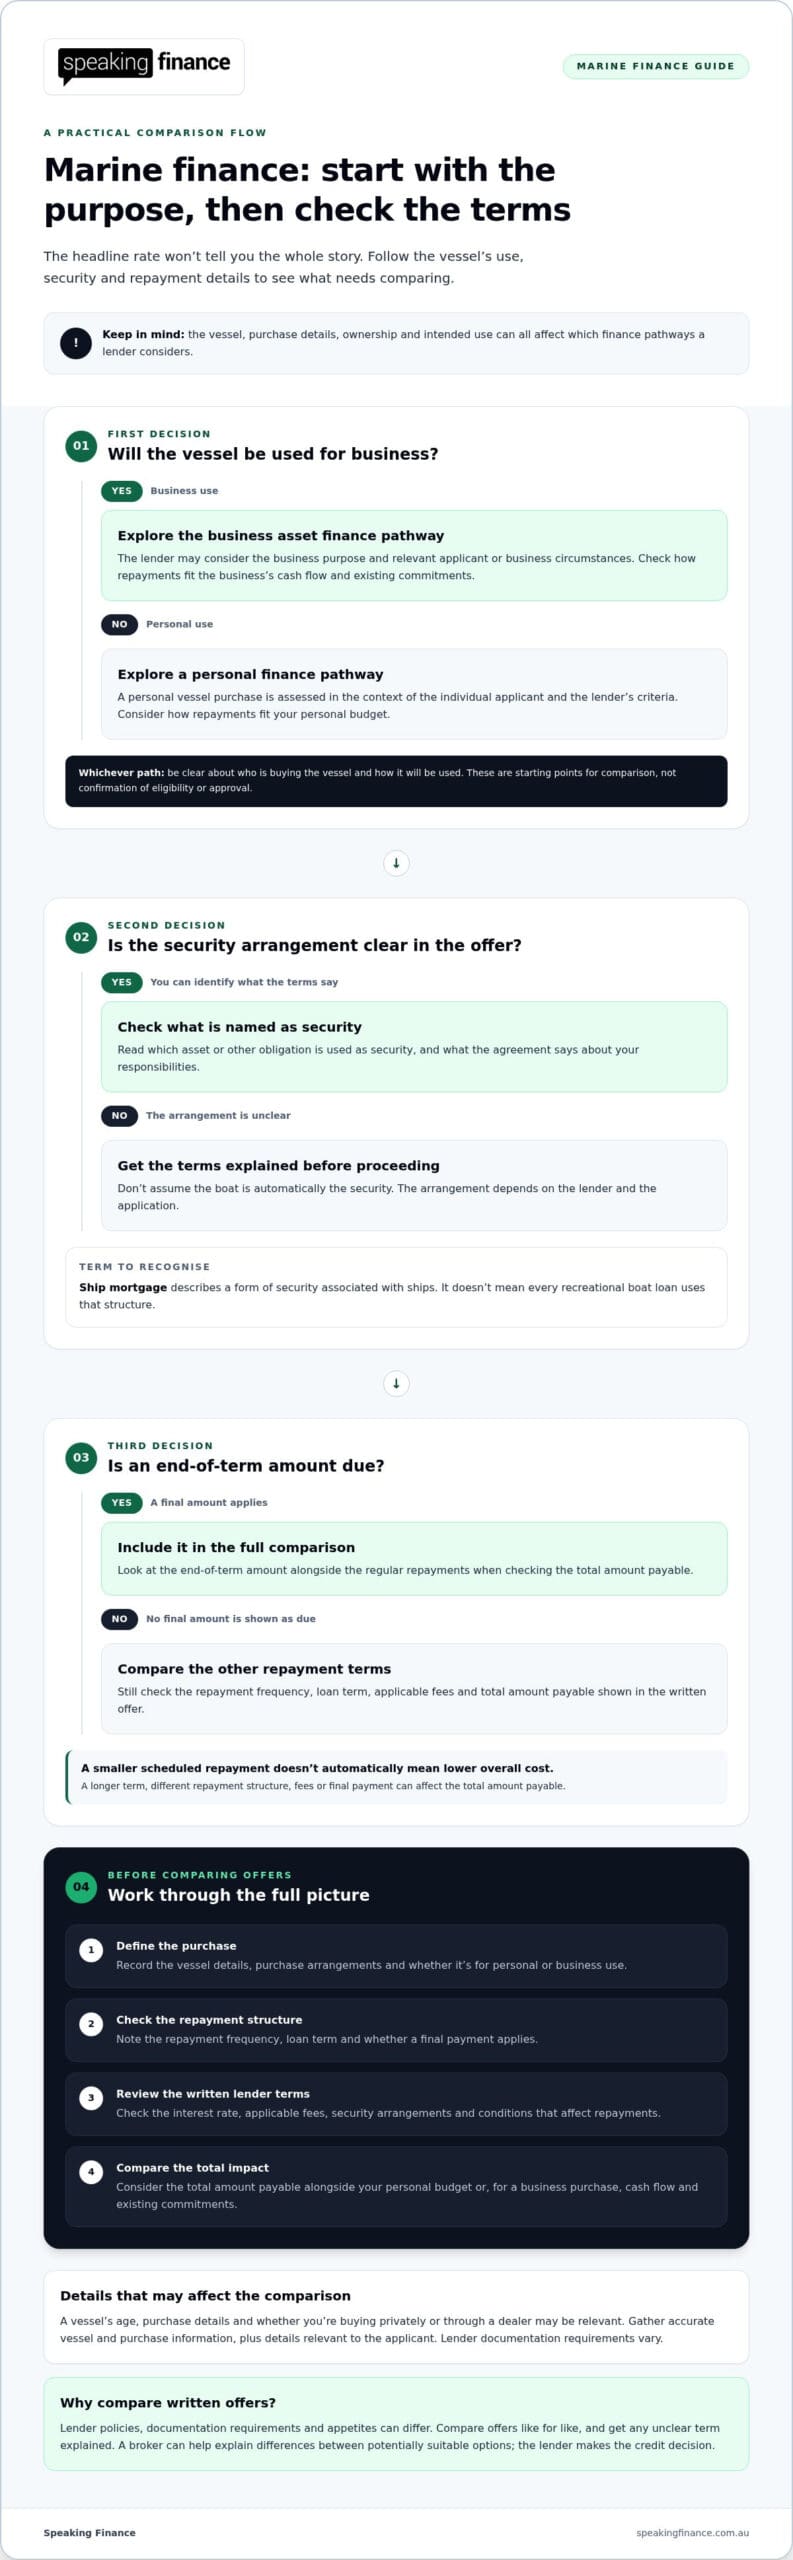
A useful comparison starts with the purchase, then checks the repayments and lender terms. Work through these steps:
- Define the purchase. Record the vessel details, purchase arrangements and whether it’s for personal or business use.
- Check the repayment structure. Note the repayment frequency, loan term and whether a final payment applies.
- Review the lender’s terms. Read the written offer, including fees, security arrangements and conditions that affect repayments.
- Compare the full picture. Consider the total amount payable alongside your personal budget or, for a business purchase, cash flow and existing commitments.
Lender policies, documentation requirements and appetites can differ materially. Clear information about the vessel, purchase and your circumstances makes it easier to see where offers differ. Avoid comparing options using a single headline figure when the loan terms or repayment structures aren’t the same.
What should you have ready for a useful comparison?
Gather accurate details about the vessel and purchase, along with information relevant to the applicant. For a personal purchase, have a clear picture of your personal circumstances. If a business is buying the vessel, set out the business purpose and relevant business information separately from personal details. This helps clarify what may be needed for each pathway, although the lender sets its own requirements.
Why is the lowest repayment not the whole comparison?
A smaller scheduled repayment can reflect a longer term or a different repayment structure. Fees and a final payment may also affect the total amount payable. For a like-for-like comparison, check the repayment frequency, loan term, applicable fees and total payable in the written offer. Consider whether the payment pattern fits your personal budget or business cash flow.
A broker can help explain lender terms and compare potentially suitable finance options. If you’d like to discuss marine finance, get in touch with Speaking Finance at a pace that suits you. The lender assesses the application and makes the credit decision.
How can a marine finance broker help you move forward?
Speaking Finance is a finance brokerage, not a lender. We can help you understand potentially suitable marine finance pathways and differences between lender requirements. Different lenders can have different credit policies, documentation requirements and appetites. The lender assesses each application and determines the credit decision, pricing and final terms based on the applicant’s circumstances.
What happens when you work with Speaking Finance?
The process starts with understanding what you’re looking to achieve. From there, we help identify possible pathways and organise the information needed for an application.
- We discuss your purpose, circumstances and objectives.
- We identify potentially suitable finance pathways and lenders.
- We explain key requirements and differences in plain English.
- We collect and organise the information needed for an application.
- We present the application to an appropriate lender or lenders.
- Through the assessment, we help manage lender communication, questions and document requests.
- Where relevant, we assist with documentation and settlement, and provide post-settlement support.
Speaking Finance works with consumers and business clients, with a focus on making finance easier to understand and helping you work through the application process.
What can you expect from the next conversation?
You can start by talking through the purchase, how the vessel will be used and any questions you have about finance. The discussion can help clarify what information may be needed and which pathways could be worth exploring. You don’t need to have every detail sorted. It’s an opportunity to understand the steps and consider what could make sense for your circumstances.
Take the next step with a clearer picture
You don’t need to have every decision made before considering your next move. Start by noting what matters most: for example, understanding the full commitment, keeping repayments manageable or matching the finance structure to a business purchase. Those priorities can help you compare options against your plans.
Take the time you need to review the details and decide what questions remain. Speaking Finance can help you work through a practical next step and explain finance options without pressure to proceed.
With a clearer sense of your priorities, you can approach the next conversation feeling more prepared.
Frequently Asked Questions
Can I apply for a marine loan before choosing a boat?
You can discuss finance pathways before choosing a specific boat, but a lender may need details of the vessel and purchase to assess an application. For an early conversation, outline the type of boat you’re considering, its intended use and your circumstances. An initial discussion can help clarify possible next steps, but it isn’t confirmation that finance will be approved.
Can marine finance be used to buy a boat from a private seller?
It may be possible, depending on the lender, vessel and application. A private sale can involve different checks from a dealer purchase, so keep the seller’s details, boat information and agreed purchase details handy. You can also consider a Personal Property Securities Register (PPSR) check for recorded interests in the boat before proceeding with the sale.
Does paying a larger deposit guarantee marine loan approval?
No. A larger deposit may reduce the amount you’re seeking to borrow, but it doesn’t guarantee approval. The lender assesses the application against its policies and your circumstances, which may include income, expenses and credit history. Before committing funds, understand the sale terms and what happens if finance isn’t approved.
Can a boat trailer or accessories be included in marine finance?
Possibly, depending on the lender’s product and how the purchase is structured. Some finance options may consider related items with the vessel, while others may treat them separately. List the trailer or accessories and their costs clearly in your enquiry, then check the written offer to see exactly what the finance covers.
Article by
Steven Emms
Steven Emms is the Director of Speaking Finance, an Australian finance brokerage based in Melbourne, Victoria.
Steven and his team help consumers, sole traders and businesses navigate vehicle finance, equipment finance, business lending, working capital and personal finance. His approach is simple: explain finance in plain English, cut through unnecessary jargon and help clients make informed decisions.
At Speaking Finance, the philosophy is simple: **We make finance black and white.**
Outside of finance, Steven is a long-suffering Essendon supporter, which has given him plenty of practice managing expectations and dealing with disappointment.
Disclaimer
The information in this article is general in nature and is provided for educational purposes only. It does not take into account your personal circumstances, financial situation, needs or objectives and should not be relied upon as personalised financial or credit advice.
Speaking Finance is a finance brokerage, not a direct lender. Finance products, interest rates, fees, terms and eligibility criteria vary between lenders and are subject to individual assessment, applicable lending policies and approval. No finance approval or particular outcome is guaranteed.
Information is believed to be accurate at the time of publication but may change. Before making financial decisions, consider your circumstances and seek appropriate independent professional advice where necessary.